
Gross Profit in Plain English
Gross profit is the amount of revenue left after a company subtracts the direct cost of the goods or services it sold. It shows how much the company earned from its core sales before accounting for many other business expenses.
In company financial analysis, gross profit helps readers examine the basic economics of producing and selling a product or delivering a service. It is an important starting point, but it is not the company’s final profit.
What Gross Profit Means

Revenue is the money a company generates from selling its goods or services before expenses are deducted. It may also be described as sales or net sales on an income statement.
Direct costs are costs closely connected with the goods or services sold. Depending on the business, they may include inventory costs, raw materials, production labor, shipping related to production, or other costs assigned to delivering a service.
Gross profit is what remains after those costs are subtracted from revenue. It represents the amount available to cover other expenses, such as marketing, office salaries, research, interest, and taxes.
Gross profit generally excludes selling, general, and administrative expenses. It also usually excludes interest and income taxes. However, companies can classify costs differently, so readers should review the company’s financial statement labels and notes.
Why Gross Profit Matters to Investors
Gross profit provides a basic view of whether a company’s sales are generating enough money to exceed the costs directly associated with those sales. This can help readers understand the economics of the company’s main products or services.
The company must use its gross profit to cover many remaining expenses. A business can therefore report positive gross profit and still have an operating loss or net loss if its other expenses are greater than the amount remaining.
Comparing gross profit across reporting periods may help identify changes in sales volume, selling prices, product mix, production costs, or service-delivery costs. A change in gross profit does not reveal the cause by itself, so the income statement, financial statement notes, and management’s explanations may provide important context.
Gross profit cannot determine investment quality on its own. Company size, industry, cost classification, gross margin, operating expenses, debt, cash flow, and reporting period all affect how the number should be interpreted.
How to Calculate Gross Profit

The basic relationship is:
Gross profit = Revenue − Cost of goods sold
Cost of goods sold, often shortened to COGS, represents costs assigned to the goods a company sold during the reporting period. A retailer’s COGS may include the cost of purchased inventory. A manufacturer’s COGS may include materials, production labor, and certain production overhead costs.
For a service business, a similar line may be called cost of revenue, cost of services, or another comparable term. The included costs depend on the company’s business model and accounting presentation.
On an income statement, revenue usually appears near the top. COGS or cost of revenue is commonly presented below revenue. Gross profit may then appear as a subtotal. If a company does not present the subtotal, a reader may be able to calculate it when the relevant revenue and cost figures are clearly disclosed.
Terminology and cost classification can differ among companies. Before calculating or comparing gross profit, readers should confirm which figures are being used and whether they cover the same reporting period.
Hypothetical Gross Profit Example

Hypothetical example: A fictional bakery records $10,000 of revenue during a reporting period. The ingredients, packaging, and other production costs assigned to the items sold total $6,000.
The calculation is:
$10,000 revenue − $6,000 direct costs = $4,000 gross profit
The $4,000 gross profit shows what remains after the bakery covers the costs assigned to producing the items it sold. That amount is available to cover other expenses, including rent, administrative wages, marketing, interest, and taxes.
This example does not show whether the bakery earned net profit, generated cash, or represents an attractive investment. Those questions require additional financial information.
Gross Profit and Related Financial Measures
| Measure | Plain-language meaning |
|---|---|
| Revenue | Money generated from sales before expenses are deducted. |
| Cost of goods sold | Costs assigned to the goods or services sold during the period. |
| Gross profit | Revenue remaining after cost of goods sold is subtracted. |
| Gross margin | Gross profit expressed as a percentage of revenue. |
| Operating profit | Profit after operating expenses are deducted from gross profit. |
| Net profit | Profit remaining after all recognized expenses, including interest and taxes, are considered. |
Gross profit is a dollar amount. Gross margin expresses the same basic relationship as a percentage:
Gross margin = Gross profit ÷ Revenue × 100
Gross margin can make comparisons easier when companies or reporting periods have different revenue levels. Even so, meaningful comparisons require attention to the industry, business model, accounting presentation, and period covered.
Operating profit goes further down the income statement by accounting for operating expenses. Net profit goes further still by considering additional expenses and income. These measures answer different questions and should not be treated as interchangeable.
Common Gross Profit Misunderstandings
- Gross profit is not cash on hand. Revenue and expenses may be recognized at different times from the related cash receipts and payments.
- Gross profit is not net profit. A company still has other expenses to pay after calculating gross profit.
- Gross profit is not an investment return. It is a company financial statement measure, not the gain or loss earned by a shareholder.
- A high gross profit does not prove financial strength. A large company may report a high dollar amount while also having substantial operating costs, debt, or other obligations.
- Gross profit figures are not automatically comparable. Company size, industry, accounting presentation, business model, and reporting period can affect the result.
Gross profit is most useful when its definition, period, and business context are understood.
Frequently Asked Questions About Gross Profit
Where does gross profit appear in financial statements?
Gross profit commonly appears on the income statement after revenue and cost of goods sold. Some companies use labels such as gross income or gross margin, while others may not present a separate subtotal.
Can gross profit be negative?
Yes. Negative gross profit occurs when the cost of goods sold or cost of revenue is greater than the related revenue for the period. This may also be described as a gross loss.
Why can gross profit change?
Gross profit can change because of sales volume, selling prices, product mix, input costs, labor costs, inventory costs, or changes in how costs are classified. The gross profit figure alone does not identify which factor caused the change.
Does every company report gross profit in the same way?
No. The labels used and the types of costs included can vary by company and industry. Some businesses, particularly those whose operations do not fit a traditional product-sales model, may present their income statements differently.
Why should the reporting period be checked?
An annual figure should not be compared directly with a quarterly figure as though they cover the same amount of time. Readers should verify the period start and end dates and determine whether the statement presents annual, quarterly, or another type of result.
Where should readers verify a company’s figures?
Readers should check the company’s official financial statements and relevant regulatory filings. The statement headings, reporting period, cost labels, and accompanying notes can help confirm what each figure represents.
Key Takeaway
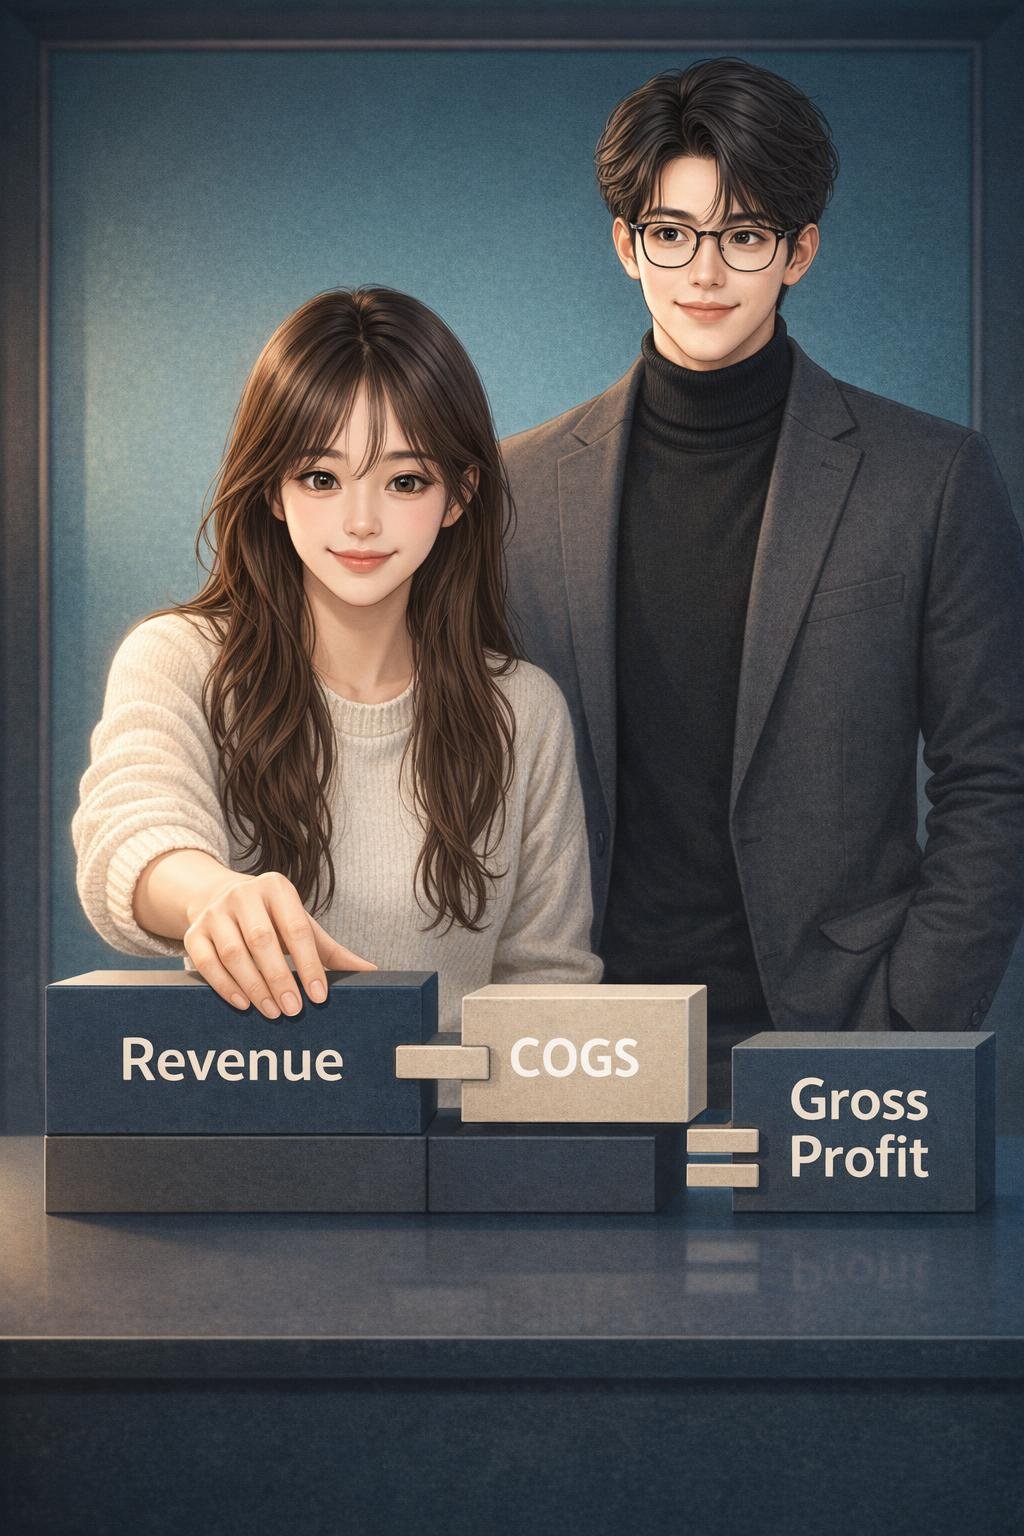
Gross profit is the revenue remaining after a company subtracts the costs assigned to the goods or services it sold. It helps readers understand the basic economics of a company’s core sales activities and its capacity to cover other expenses.
The measure should be evaluated alongside gross margin, operating expenses, net profit, cash flow, reporting periods, and the company’s accounting presentation. Gross profit is informative, but it does not provide a complete assessment of a company or an investment.
References
The following source supports the broad definition of profit as revenue minus cost. The gross-profit discussion above provides additional educational context about applying that general relationship to revenue and cost of goods sold.
- Profit | Investor.gov — https://www.investor.gov/introduction-investing/investing-basics/glossary/profit.
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product.
Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.