
Operating Income at a Glance
Operating income is the profit or loss associated with a company’s operating activities after operating costs are deducted from operating revenue and other operating income. It helps show the financial result produced by the operating category before the financial statements move to broader profit measures that may include financing, taxes, and other classified items.
A positive amount means recognized operating income exceeded operating expenses for the reporting period. A negative amount, often called an operating loss, means operating expenses exceeded operating income. The exact presentation depends on the accounting framework and classifications used in the company’s financial statements.
What Operating Income Means
In financial reporting, income generally refers to amounts recognized as increasing profit, while expenses are recognized costs that reduce profit. These amounts are recorded under accounting rules and do not necessarily represent cash received or paid during the same period.
Operating activities are the business activities classified within the operating category. For a retailer, relevant items might include sales, the cost of merchandise, employee compensation, rent, and certain administrative costs. Another type of business may have a different mix of operating income and expenses.
Operating income is therefore more than revenue minus any costs that happen to look operational. Companies must classify income and expenses according to the accounting framework they use. Readers should review the company’s financial statements and accompanying notes to understand which items were included.
Under IFRS 18, operating profit or loss is the total of income and expenses classified in the operating category. This definition also illustrates why classifications matter: an item outside that category may affect a broader profit measure without affecting operating profit or loss.
Why Operating Income Matters in Company Analysis
Operating income helps readers focus on the reported results of a company’s operations. It can be useful when examining whether revenue was sufficient to cover costs such as the cost of products or services, employee compensation, facility costs, depreciation, and other expenses classified as operating.
The metric may also help a reader study changes over time. For example, revenue could rise while operating income falls if operating costs grow faster than revenue. Conversely, operating income could improve if revenue increases faster than operating expenses or if the company reduces those expenses.
Operating income is not a complete measure of financial health. It does not, by itself, explain cash availability, debt, financing costs, taxes, asset values, future obligations, or the sustainability of reported results.
It also cannot determine whether a stock is attractive. Company analysis normally requires multiple financial statements, several reporting periods, relevant disclosures, and an understanding of the business and its risks.
How Operating Income Is Calculated
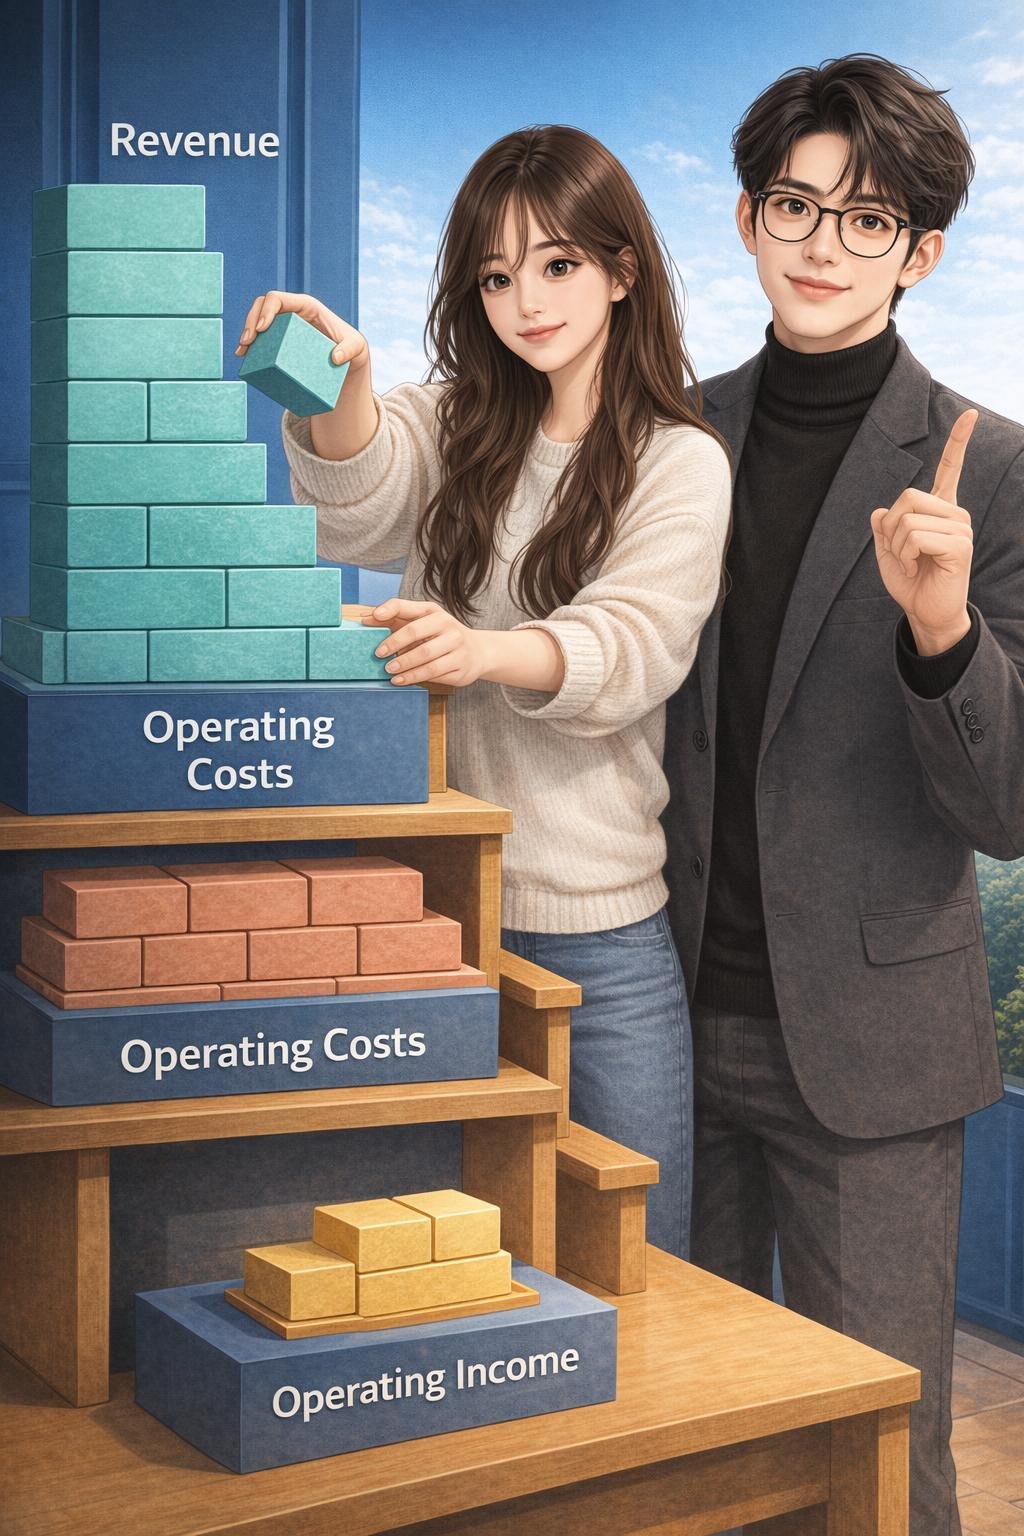
A simplified operating income relationship is:
Operating income = operating revenue and other operating income − operating costs and expenses
In a common presentation, the calculation may begin with revenue. The company then subtracts the cost of producing or obtaining the goods and services sold. This produces gross profit when the company presents that subtotal.
Operating expenses are then deducted. Depending on the business and its accounting presentation, these may include selling costs, general and administrative expenses, research and development costs, depreciation, amortization, and other items classified as operating.
The calculation can also include other operating income or expenses. As a result, the following expanded relationship is only a general learning model:
Operating income = revenue − cost of revenue − operating expenses + other operating income − other operating expenses
Interest, income taxes, investing-category items, and other amounts classified outside the operating category may affect broader profit measures rather than operating income. However, labels and classifications can vary with the applicable accounting framework and the nature of the company’s business.
Readers should use the calculation presented in the relevant financial statements rather than assuming every company classifies similarly named items in the same way. The notes may provide important details about expenses, unusual items, accounting policies, and changes in presentation.
Hypothetical Operating Income Example
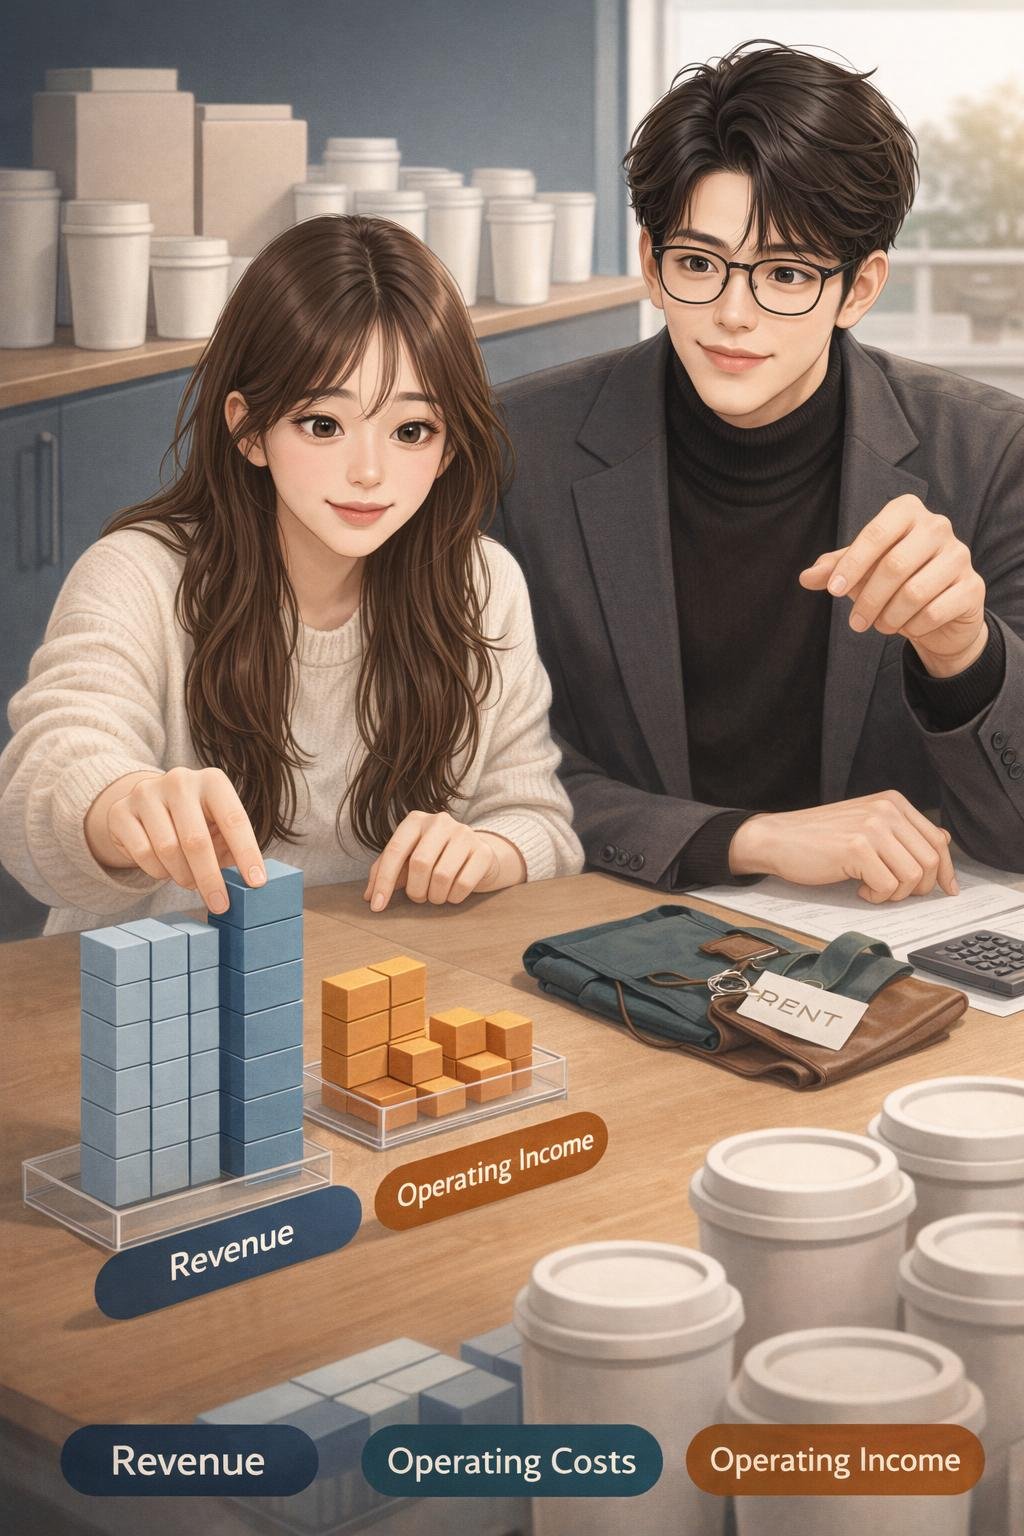
Hypothetical example: Consider a fictional business called Plain Cup Company. The following invented figures are for education only and are not financial data from a real company.
| Hypothetical item | Amount |
|---|---|
| Revenue | $500,000 |
| Cost of products sold | $280,000 |
| Employee, rent, and administrative expenses | $150,000 |
First, subtract the $280,000 cost of products sold from $500,000 of revenue. The result is $220,000 of gross profit.
Next, subtract $150,000 of operating expenses from the $220,000 gross profit:
$220,000 − $150,000 = $70,000 of operating income
In this simplified example, the fictional company recognized $70,000 more operating income than operating expenses during the period. This does not mean it generated $70,000 of cash or finished with $70,000 of net income. Items outside the operating calculation could change the company’s final profit, and cash receipts and payments may occur at different times.
If the fictional company’s operating expenses had exceeded its operating income, the result would have been an operating loss. That result would describe the period in the example rather than predict what would happen in a future period.
How to Interpret Operating Income
One way to interpret operating income is to compare it across several reporting periods. Use comparable periods, such as one full fiscal year against another full fiscal year, because a quarter and a full year cover different lengths of time.
Look at revenue at the same time. Rising operating income can have a different meaning when revenue is also rising than when revenue is falling and the improvement comes mainly from cost reductions.
Operating margin places operating income in relation to revenue. The basic calculation is:
Operating margin = operating income ÷ revenue × 100
This percentage indicates how much operating income was reported for each unit of revenue. It can make differently sized periods or businesses easier to examine, but it still requires context.
Check whether accounting policies, business structure, acquisitions, disposals, or expense classifications changed between periods. A comparison can be misleading if the underlying figures were prepared or classified differently.
Industry and business-model differences also matter. Companies can have different cost structures even when they report similar revenue. Operating income is most useful when considered alongside cash flow, assets, liabilities, net income, disclosures, and other relevant measures.
Operating Income vs. Related Profit Measures
| Measure | What it generally describes | How it differs from operating income |
|---|---|---|
| Gross profit | Revenue minus the direct cost of the goods or services sold. | It is calculated before many other operating expenses are deducted. |
| Net income | The final profit or loss after all recognized income and expenses included in the profit calculation. | It can include financing costs, taxes, and other items outside operating income. |
| Operating cash flow | Cash generated or used by operating activities, as reported in the statement of cash flows. | It focuses on cash flows rather than accounting profit and includes adjustments for noncash items and working-capital changes. |
| Operating margin | Operating income expressed as a percentage of revenue. | It is a ratio, while operating income is an amount of profit or loss. |
| EBIT | Earnings before interest and taxes. | It may resemble operating income, but the two are not automatically interchangeable because their included items and definitions can differ. |
Gross profit provides an earlier subtotal in the income statement. It focuses on revenue after the direct cost of sales but before many costs required to operate the wider business.
Net income is broader. A company may report positive operating income but lower net income, or even a net loss, after financing costs, taxes, and other non-operating items are included.
Operating cash flow answers a different question. Accounting profit can include revenue not yet collected in cash, expenses not yet paid, and noncash expenses such as depreciation. Operating income and operating cash flow can therefore move differently.
EBIT is a commonly used abbreviation for earnings before interest and taxes. It should not be assumed to equal operating income without checking how the company or analyst calculated it. Non-operating items may be included in one measure but excluded from the other.
Frequently Asked Questions About Operating Income
Where does operating income appear in financial statements?
Operating income may appear as a subtotal in the statement of income, statement of operations, or another similarly titled performance statement. Terminology and presentation can vary, so readers should also review the statement headings and accompanying notes.
Can operating income be negative?
Yes. When operating expenses exceed operating income for a reporting period, the result is an operating loss. A loss describes the reported period and does not by itself establish the company’s future results.
Is operating income the same as EBIT?
Not necessarily. EBIT means earnings before interest and taxes, but its calculation may include items that are not classified as operating. The two figures can be equal in some presentations, but readers should compare their definitions and components before treating them as equivalent.
Is operating income the same as net income?
No. Net income reflects a broader set of recognized income and expenses. Operating income focuses on items within the operating category, while net income can also reflect financing costs, taxes, and other classified items.
Why can companies with similar revenue have different operating income?
Companies can have different product costs, staffing needs, rent, research spending, depreciation, pricing, scale, and administrative expenses. Their accounting classifications and business models may also differ. Similar revenue therefore does not imply similar operating results.
Does higher operating income always mean a company is improving?
No. The increase might come from revenue growth, lower expenses, a classification change, or an item that may not recur. A useful review considers the cause of the change, the reporting period, cash flow, disclosures, and other financial measures.
Can operating income identify an attractive stock?
No single metric can determine investment quality. Operating income does not capture every financial obligation, risk, valuation factor, cash-flow issue, or business condition that may be relevant to an investment decision.
Key Takeaway
Operating income measures the profit or loss produced by income and expenses classified within a company’s operating category. In a simplified calculation, it is operating revenue and other operating income minus operating costs and expenses.
The figure can help readers examine operating performance, but it should not be interpreted alone. Check the applicable accounting presentation, use consistent reporting periods, review the company’s classifications and notes, and consider related measures such as revenue, operating margin, net income, and operating cash flow within the wider company context.
References
- IFRS – IFRS 18 Presentation and Disclosure in Financial Statements—Key terms: https://www.ifrs.org/supporting-implementation/supporting-materials-by-ifrs-standards/ifrs-18/key-terms/
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only. They should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.