
Income Statement: A Simple Definition
An income statement is a financial statement that reports a company’s revenue, expenses, taxes, and resulting net income or loss over a stated reporting period.
In simple terms, it shows how much money a company generated, what costs it incurred, and whether it recorded a profit or loss during that period.
What an Income Statement Means
An income statement summarizes a company’s financial activity over time. The reporting period might be a quarter, a fiscal year, or another clearly identified period.
This is different from a statement that describes the company at one particular date. When reading an income statement, check the beginning and ending dates shown in its heading so that you know exactly which period the numbers cover.
An income statement may also be called a statement of earnings, statement of operations, or profit-and-loss statement. The precise title and presentation can vary, but the basic purpose remains the same.
Why the Income Statement Matters to Investors
Investors use an income statement to understand how a company generated revenue and how various costs affected its results. It can help a reader see whether revenue was sufficient to cover expenses and taxes during the stated period.
Comparing income statements from different periods can also reveal changes in revenue, expenses, and profit or loss. However, those changes need context. A higher expense may reflect a temporary event, a change in operations, or another factor explained in the financial statement notes.
An income statement alone cannot determine whether a security is suitable for a particular person. Investors generally need to consider the company’s other financial statements, disclosures, risks, circumstances, and broader information before making their own decisions.
How an Income Statement Works
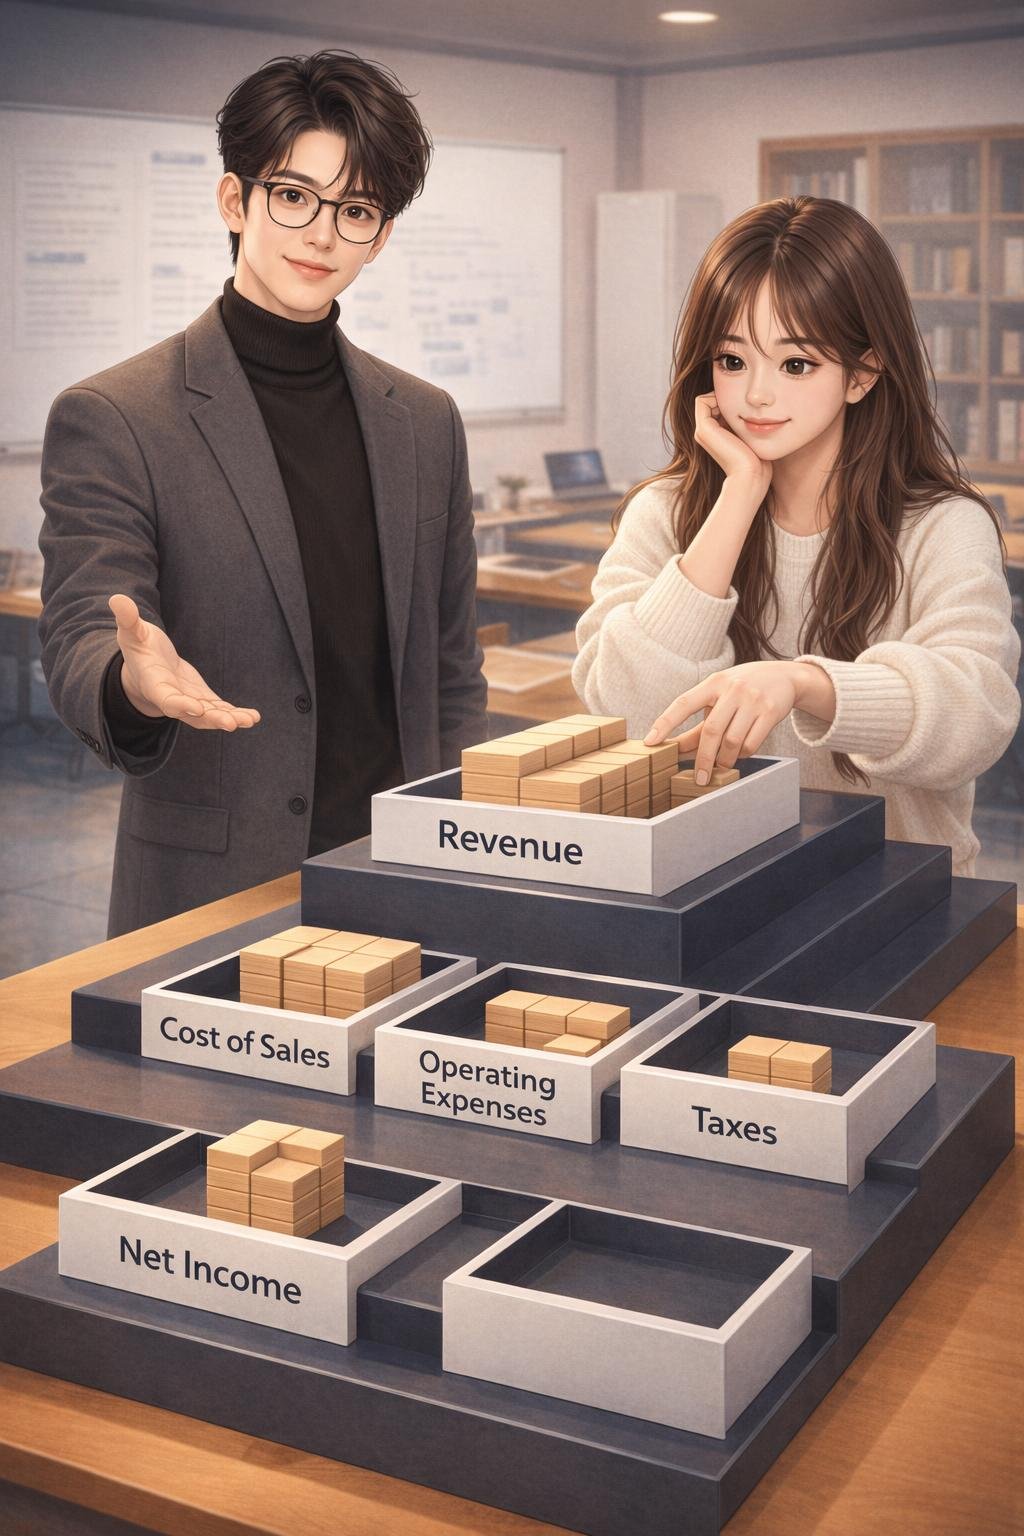
The basic idea is that a company starts with revenue and subtracts its costs, expenses, and taxes to arrive at net income or a net loss.
The main categories commonly include:
- Revenue: Amounts generated by the company’s business activities during the reporting period.
- Cost of revenue or cost of sales: Costs directly connected with providing the goods or services that produced revenue.
- Gross profit: Revenue remaining after subtracting cost of revenue or cost of sales.
- Operating expenses: Costs associated with running the business, such as administrative or selling expenses.
- Operating income or loss: The result after operating expenses are deducted from gross profit.
- Non-operating items: Income or expenses that are not part of the company’s main operating activities, depending on how the statement is presented.
- Taxes: The income tax expense reported for the period.
- Net income or net loss: The final result after the reported expenses and taxes have been accounted for.
Not every company uses identical labels or presents every subtotal in the same way. Readers should therefore focus on what each line represents rather than relying only on its label.
The reporting period is essential because an income statement measures activity over time. Figures from periods of different lengths may not be directly comparable. Comparative amounts from an earlier period can help a reader identify changes, but they do not explain those changes by themselves.
The accompanying notes are also important. They provide accounting details and explanations that may not fit on the face of the statement, including information needed to understand particular line items and accounting policies.
Where to Find an Income Statement
Income statements appear in company financial reports. For a U.S. public company, the audited financial statements in Item 8 of its annual Form 10-K include an income statement, which may instead be titled a statement of earnings or statement of operations.
The notes that accompany the financial statements should be reviewed with the income statement because they help explain the reported figures. Investor.gov also explains that U.S. company financial statements are prepared under generally accepted accounting principles, commonly abbreviated as GAAP, and that the annual financial statements in a Form 10-K are audited by an independent accountant.
Readers should verify company figures using the relevant filing or another current official company source. They should also confirm the form type, reporting period, and filing date before comparing information.
Hypothetical Income Statement Example
Hypothetical educational example: The following figures describe a fictional business. They are not financial data from a real company.
| Income statement item | Hypothetical amount |
|---|---|
| Revenue | $100,000 |
| Cost of sales | $40,000 |
| Gross profit | $60,000 |
| Operating expenses | $35,000 |
| Operating income | $25,000 |
| Other expense | $5,000 |
| Income before taxes | $20,000 |
| Income tax expense | $4,000 |
| Net income | $16,000 |
In this fictional example, the business begins with $100,000 of revenue. After subtracting $40,000 in cost of sales, it has $60,000 in gross profit. Operating expenses reduce that amount to $25,000 in operating income.
After a hypothetical $5,000 other expense and $4,000 income tax expense, the fictional business reports $16,000 in net income. If total expenses and taxes had exceeded revenue, the final result would instead have been a net loss.
All amounts in this example are invented solely to demonstrate the calculation and should not be treated as reported company information.
Income Statements and Related Financial Concepts
Balance Sheet
A balance sheet reports a company’s assets, liabilities, and owners’ equity at a particular date. Unlike an income statement, which covers activity over a period, a balance sheet describes the company’s financial position at one point in time.
Cash Flow Statement
A cash flow statement reports cash moving into and out of a company through operating, investing, and financing activities. It helps explain changes in cash and is not the same as the calculation of net income.
Financial Statement Notes
Financial statement notes accompany the main statements and provide additional explanations. They can describe accounting policies, break down particular figures, and supply context needed to interpret the statements.
Net Income
Net income is the amount remaining after the reported expenses and taxes are deducted from revenue and other reported income. When the calculation produces a negative result, it is generally described as a net loss.
Other Comprehensive Income
Under International Financial Reporting Standards, or IFRS, other comprehensive income consists of income and expense items that applicable IFRS Standards do not recognize in profit or loss. It is therefore distinct from the period’s profit or loss.
IFRS presentation requirements allow profit or loss and other comprehensive income to appear in one combined statement or in two separate statements. This presentation should not be confused with the basic income statement structure used in the hypothetical example above.
Common Income Statement Misunderstandings

Net income is not the same as cash on hand
Accounting rules can recognize revenue or expenses at a different time from the related cash receipt or payment. A profitable period therefore does not necessarily mean that the company’s cash increased by the same amount. The cash flow statement provides information about actual cash movements.
An income statement does not show one instant in time
An income statement covers a reporting period with a beginning and ending date. The balance sheet, by contrast, presents financial position as of a specific date.
One profitable period does not guarantee future results
An income statement reports historical results for its stated period. It does not predict future revenue, expenses, profits, losses, or stock performance.
A single figure rarely provides enough context
Net income can be useful, but it should not be read in isolation. Revenue trends, expenses, cash flows, assets, liabilities, accounting explanations, risks, and unusual items may all affect how the result is understood.
Income Statement FAQ
Is an income statement the same as a profit-and-loss statement?
Yes. Profit-and-loss statement is an alternate name for an income statement. Statement of earnings and statement of operations are also commonly used names.
What period does an income statement cover?
It covers the reporting period stated in the document’s heading. Before interpreting the figures, check the exact beginning and ending dates and whether the period is annual, quarterly, or another length.
Where does the income statement appear in a Form 10-K?
The audited financial statements in Item 8 of a U.S. annual Form 10-K include an income statement. Its title may instead use wording such as statement of earnings or statement of operations.
What does a net loss mean?
A net loss means the calculation of reported revenue, income, expenses, and taxes resulted in a negative final amount for the stated period. The notes and other disclosures may help explain the factors behind that result.
Why compare the income statement with other financial statements?
Each financial statement answers different questions. The income statement reports financial performance over a period, the balance sheet reports financial position at a date, and the cash flow statement reports cash movements. Reading them with the accompanying notes provides more context than relying on one statement or line item.
Key Takeaway
An income statement shows a company’s revenue, expenses, taxes, and resulting net income or loss over a stated reporting period. It helps explain how the company arrived at its reported profit or loss, but it does not provide a complete picture by itself.
The statement is most useful when readers confirm its reporting period, review comparative amounts, read the accompanying notes, and consider the balance sheet, cash flow statement, and other relevant disclosures together.
References
- https://www.investor.gov/introduction-investing/investing-basics/glossary/financial-statement
URL: https://www.investor.gov/introduction-investing/investing-basics/glossary/financial-statement
- IFRS – IAS 1 Presentation of Financial Statements
URL: https://www.ifrs.org/issued-standards/list-of-standards/ias-1-presentation-of-financial-statements/
- How to Read a 10-K/10-Q | Investor.gov
These sources support the article’s definition, filing guidance, and discussion of financial statement presentation.
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.