
What Is Net Income?
Net income is the profit a company has left after subtracting all of its expenses from all of its revenue during a specific period.
Revenue is the money a company earns from selling goods or services and from certain other activities. Expenses are the costs the company incurs to operate, borrow money, pay taxes, and conduct its business.
Net income is often called the company’s “bottom line” because it usually appears near the bottom of the income statement. An income statement is a financial report showing a company’s revenue, expenses, and profit or loss over a period such as three months or one year.
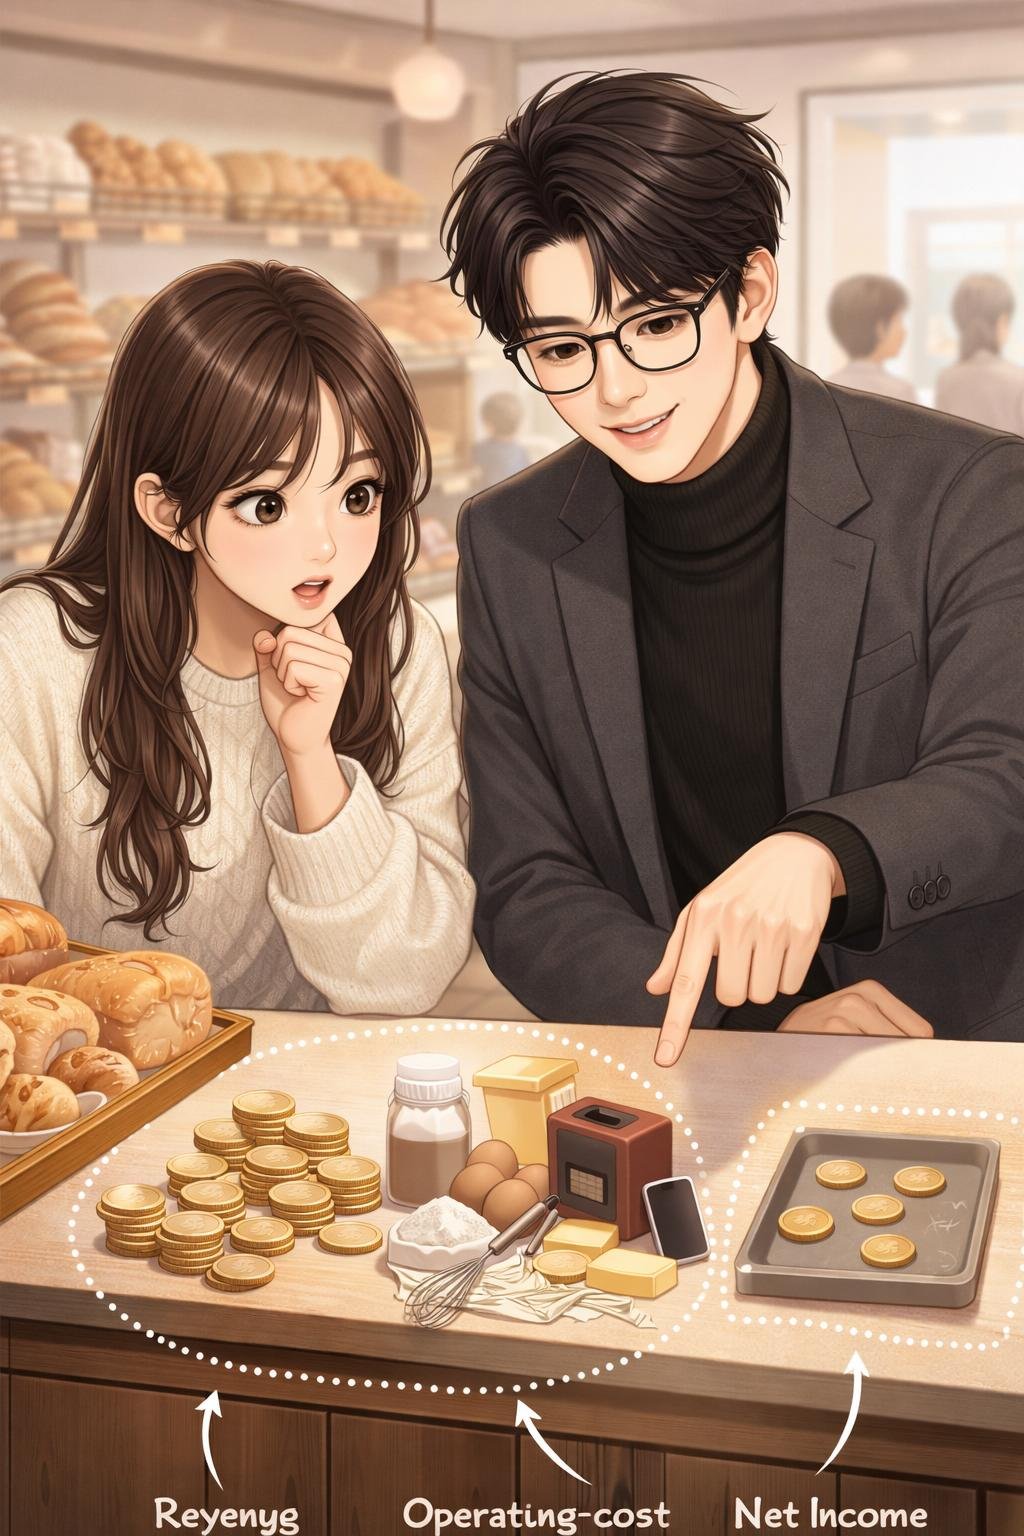
A simple way to think about net income is to imagine a small store. The store collects money from customers, but it must also pay for products, employee wages, rent, utilities, loan interest, and taxes. Whatever remains after those costs is its net income.
If expenses are greater than revenue, the result is negative. This is commonly called a net loss.
How Does Net Income Work?
Net income is calculated for a specific reporting period. Public companies commonly report results for quarters and full fiscal years. A fiscal year is the 12-month period a company uses for financial reporting. It does not always match the calendar year.
The basic formula is:
Net income = Total revenue − Total expenses
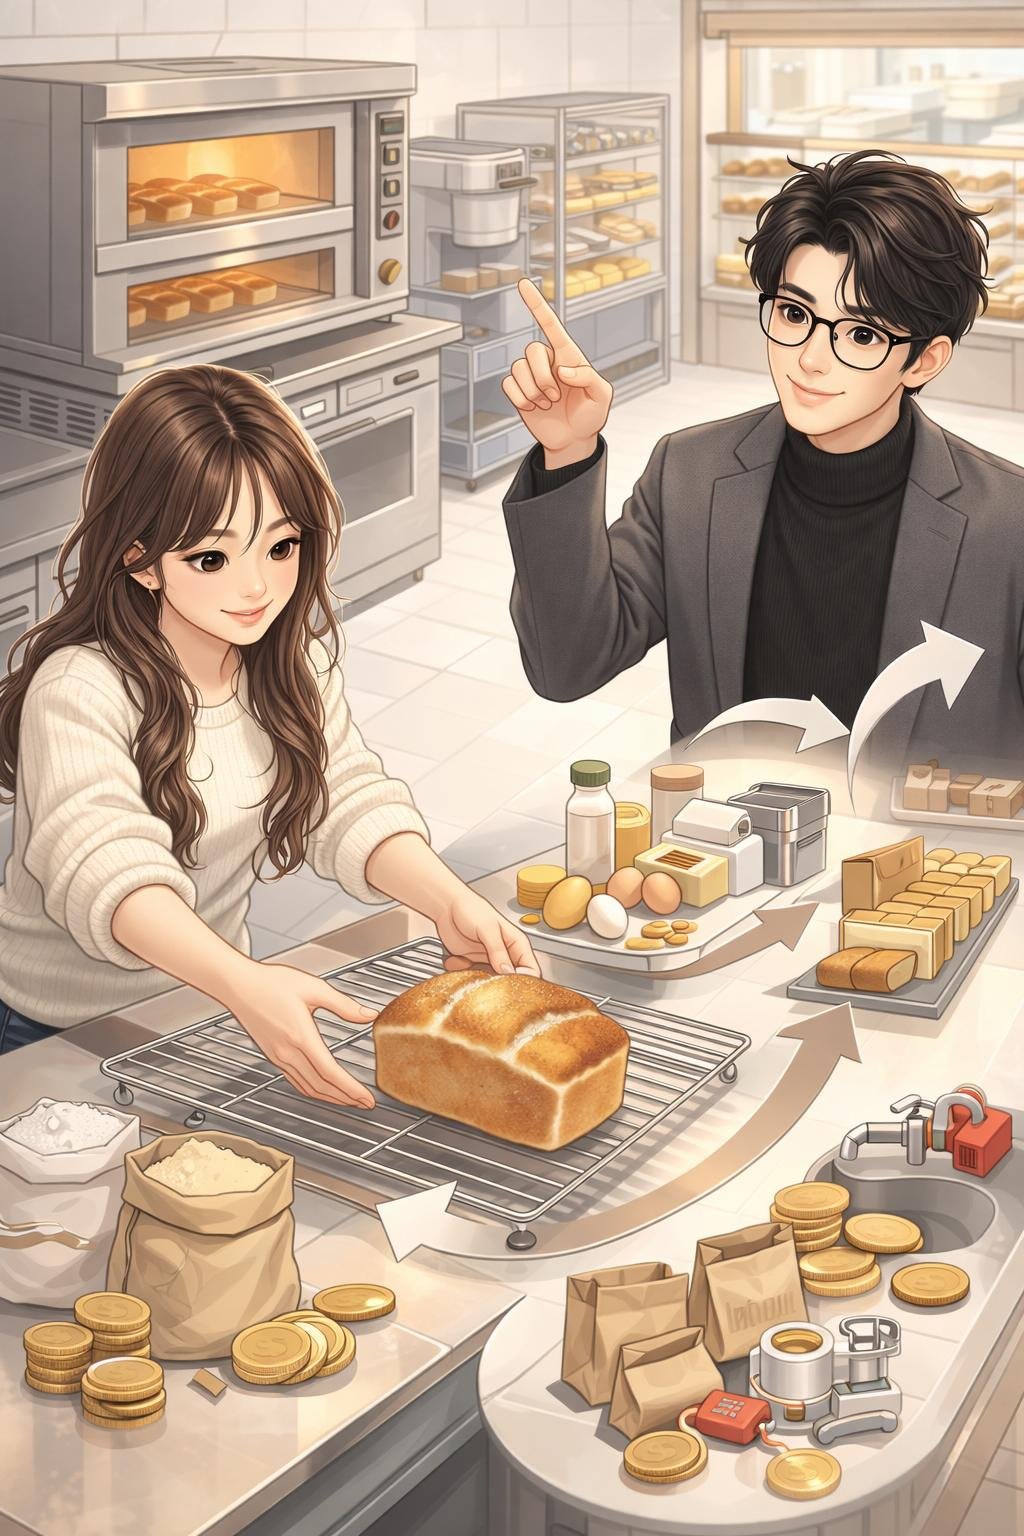
This formula looks simple, but total expenses can include several different categories.
Revenue
Revenue is the amount a company earns before expenses are deducted. It may come from product sales, service fees, subscriptions, licensing, or other business activities.
Revenue is sometimes called the “top line” because it generally appears near the top of the income statement. Revenue is not the same as profit. A company can report high revenue and still have a net loss if its expenses are even higher.
Cost of Revenue or Cost of Goods Sold
Cost of goods sold, often shortened to COGS, includes the direct costs of producing the goods a company sells. For a manufacturer, these costs might include materials and production labor.
Some service and technology companies use the term cost of revenue instead. This may include costs directly connected to providing their services.
Subtracting these direct costs from revenue produces gross profit.
Gross profit = Revenue − Cost of goods sold or cost of revenue
Operating Expenses
Operating expenses are costs associated with running the business that are not included in the direct cost of producing its goods or services.
Examples may include marketing, office rent, administrative salaries, research and development, and certain technology costs.
Subtracting operating expenses from gross profit generally produces operating income. Operating income measures profit from the company’s main business operations before certain non-operating items and income taxes.
Interest, Taxes, and Other Items
A company may pay interest expense on borrowed money. It may also earn interest on cash or investments.
The company may record gains or losses from activities outside its main operations. It may also recognize unusual charges, asset write-downs, or gains from selling property or a business division.
Finally, income tax expense is deducted. After these items are included, the company reaches net income.
The exact order and labels can differ among companies. Accounting rules and the nature of the business affect how the income statement is presented.
Simple Example
Consider a hypothetical company called Example Furniture Company. The numbers below are invented only to explain the calculation. They do not describe a real company or investment.
Assume the company reports the following results for one year:
- Revenue: $1,000,000
- Cost of goods sold: $550,000
- Operating expenses: $250,000
- Interest expense: $20,000
- Income tax expense: $45,000
First, subtract the cost of goods sold from revenue:
$1,000,000 − $550,000 = $450,000 gross profit
Next, subtract operating expenses:
$450,000 − $250,000 = $200,000 operating income
Then subtract interest expense:
$200,000 − $20,000 = $180,000 income before taxes
Finally, subtract income tax expense:
$180,000 − $45,000 = $135,000 net income
In this hypothetical example, the company’s net income is $135,000 for the year. This means it recorded $135,000 of accounting profit after the listed expenses.
Now suppose the same company had $200,000 of income before taxes but recorded $230,000 of taxes and other expenses. Its final result would be negative $30,000. That would be reported as a net loss rather than positive net income.
Net income may also be expressed as a percentage of revenue using net profit margin:
Net profit margin = Net income ÷ Revenue × 100
For the original example:
$135,000 ÷ $1,000,000 × 100 = 13.5%
This means the company recorded 13.5 cents of net income for each dollar of revenue during that period. It does not mean the company holds that amount in cash, and it does not predict what the margin will be in future periods.
Why Does Net Income Matter?
Investors frequently encounter net income in earnings releases, annual reports, quarterly reports, financial websites, and stock research tools. It provides a broad summary of whether a company recorded an overall profit or loss for the reporting period.
Net income helps investors examine several questions:
- Did the company record a profit after all reported expenses?
- Is profit increasing, decreasing, or changing unpredictably over time?
- How much profit did the company produce relative to its revenue?
- How does its profitability compare with similar businesses?
- What effect did interest, taxes, or unusual items have on results?
Net income also connects to earnings per share, or EPS. EPS generally shows how much of a company’s earnings is associated with each common share, using a weighted average share count for the period. “Weighted average” means the calculation adjusts for changes in the number of shares during that period.
However, net income cannot explain the entire condition of a business. It does not show the company’s total debt, the value of its assets, its competitive position, or the amount of cash available at a particular moment.
It also cannot show whether a stock’s market price is reasonable. A profitable company can have an expensive stock price, while a company reporting a temporary loss may still own valuable assets or have other characteristics investors examine.
How Beginners Can Interpret Net Income
A useful starting point is to examine net income across several comparable reporting periods. One period alone may be affected by temporary events.
For example, investors might compare a quarter with the same quarter one year earlier. This can be more meaningful than comparing it with the immediately preceding quarter when the business is seasonal. A seasonal business earns different amounts at different times of the year because customer demand changes with holidays, weather, or other recurring patterns.
Beginners can also compare changes in revenue with changes in net income. If revenue rises but net income falls, expenses may be growing faster than sales. If net income grows faster than revenue, margins may be improving. The reason still needs investigation because a tax benefit, asset sale, or other non-recurring item could have caused the change.
Comparisons are generally most useful between companies in the same industry. Different industries have different cost structures, borrowing needs, tax situations, and typical profit margins. A manufacturer, bank, software provider, and grocery business may report very different margins even when each operates successfully.
Investors should also check which version of net income is being discussed. A financial report may show consolidated net income, which includes the combined results of a parent company and businesses it controls.
It may then show net income attributable to noncontrolling interests and net income attributable to the parent company. A noncontrolling interest represents ownership held by outside investors in a business that the reporting company controls but does not own completely.
The figure attributable to the parent company is often the amount most closely connected to the earnings available to that company’s shareholders. Labels differ, so readers should examine the statement carefully.
Limitations and Common Mistakes
Net Income Is Not the Same as Cash Flow
One of the most important mistakes is assuming net income equals cash received. Accounting rules may recognize revenue before a customer pays or record an expense gradually over several years.
Depreciation, for example, spreads the accounting cost of certain long-lived assets across their estimated useful lives. Depreciation reduces net income, but it usually does not represent a new cash payment in the period when the expense is recorded.
The statement of cash flows helps explain how cash moved through operating, investing, and financing activities. Net income and cash flow are related, but they are not interchangeable.
One-Time Items Can Distort a Period
A company may sell property, settle a lawsuit, write down an asset, or recognize a major tax benefit. These events can sharply change net income even if the main business has changed very little.
Investors sometimes review adjusted profit measures that exclude selected items. However, adjusted measures may not follow a single standardized calculation. Companies can define them differently, so readers should examine what was removed and why.
Positive Net Income Does Not Guarantee Financial Strength
A company can report positive net income while carrying substantial debt or experiencing weak cash collection. It can also report a net loss while holding significant cash or investing heavily in expansion.
Net income should therefore be considered with the balance sheet, cash flow statement, debt levels, business risks, and notes to the financial statements.
Accounting Estimates Affect the Result
Net income is based partly on accounting judgments and estimates. These may involve the useful life of equipment, the likelihood that customers will pay, future warranty costs, inventory values, or possible legal obligations.
Reasonable changes in estimates can change reported profit. Differences in accounting methods can also make comparisons less direct.
A Larger Number Is Not Automatically Better
A large company may naturally report more net income than a small company because it generates more revenue. Comparing only the dollar amounts may reveal little about efficiency.
Net profit margin, earnings per share, return measures, and growth rates can provide additional context. None should be treated as a complete investment test by itself.
Reporting Periods Must Match
Comparing one company’s quarterly net income with another company’s annual net income would be misleading. Currency, fiscal period length, business structure, and accounting presentation should also be consistent enough for a useful comparison.
Related Beginner Terms
- Revenue: Money earned before expenses are deducted. Revenue is generally the starting point of the income statement.
- Gross profit: Revenue minus the direct cost of producing goods or providing services.
- Operating income: Profit from normal business operations before certain items such as interest and income taxes.
- Net profit margin: Net income divided by revenue. It expresses overall profit as a percentage of sales.
- Earnings per share: A calculation connecting earnings available to common shareholders with the weighted average number of common shares.
- Net loss: A negative result that occurs when total expenses exceed total revenue for a period.
- Cash flow: The movement of cash into and out of a company. Cash flow can differ significantly from net income.
- Retained earnings: The accumulated earnings a company has kept in the business rather than distributed to shareholders, adjusted for losses and certain other items.
- Income statement: The financial statement that presents revenue, expenses, and profit or loss over a defined period.
FAQ
Is net income the same as profit?
Net income is a form of profit. It is the final accounting profit after all included expenses, interest, taxes, gains, and losses. Other profit measures, such as gross profit and operating profit, are calculated earlier on the income statement.
Can net income be negative?
Yes. Negative net income is called a net loss. It means the company’s reported expenses and losses were greater than its revenue and gains during that period.
Is net income the amount of cash in a company’s bank account?
No. Net income is an accounting result measured over a period. A company’s cash balance is measured at a point in time and is affected by borrowing, asset purchases, customer payments, and many other transactions.
Where can beginners find net income?
It is generally shown near the bottom of a company’s consolidated income statement, which may also be called a statement of operations or statement of earnings. It may also appear in earnings releases and financial summaries.
Does higher net income always mean a company is improving?
No. Net income may rise because of a one-time gain, lower taxes, reduced interest expense, or another temporary event. The company’s revenue, expenses, margins, cash flow, and explanation of changes provide important context.
What is the difference between net income and operating income?
Operating income focuses mainly on profit from normal business operations. Net income goes further by including items such as interest, taxes, and certain non-operating gains or losses.
Can two companies calculate net income differently?
Companies must follow the accounting standards that apply to their reports, but differences in business activities, estimates, classifications, and ownership structures can affect presentation. Adjusted earnings measures may vary even more because they can use company-specific definitions.
Does positive net income mean a stock will rise?
No. A stock’s price reflects many factors, including expectations, valuation, financial condition, industry developments, and market conditions. Positive net income alone does not predict a future stock price.
Key Takeaway
Net income is the profit remaining after a company subtracts all reported expenses from its revenue for a specific period. It helps beginners understand whether the company recorded an overall accounting profit or loss and supports calculations such as net profit margin and earnings per share.
Its main limitation is that one final number cannot explain the quality of earnings, cash generation, financial strength, or future prospects. Net income is most informative when examined over consistent periods and considered with cash flow, revenue, debt, margins, accounting notes, and other relevant information.
Disclaimer
This article is for general educational and informational purposes only. It is not investment, financial, legal, or tax advice. Financial information and market conditions can change. Readers should verify current information and consider their own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images in this article may be AI-generated educational illustrations. They are provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.