
Price-to-Book Ratio at a Glance
The price-to-book ratio, commonly abbreviated as the P/B ratio, compares a company’s stock price per share with its book value per share. Book value is an accounting measure of the company’s net assets.
In simple terms, the ratio shows how much the market is pricing each share relative to the accounting value assigned to the company’s net assets. It is a comparison tool, not a complete judgment about whether a stock is fairly valued.
What the Price-to-Book Ratio Means
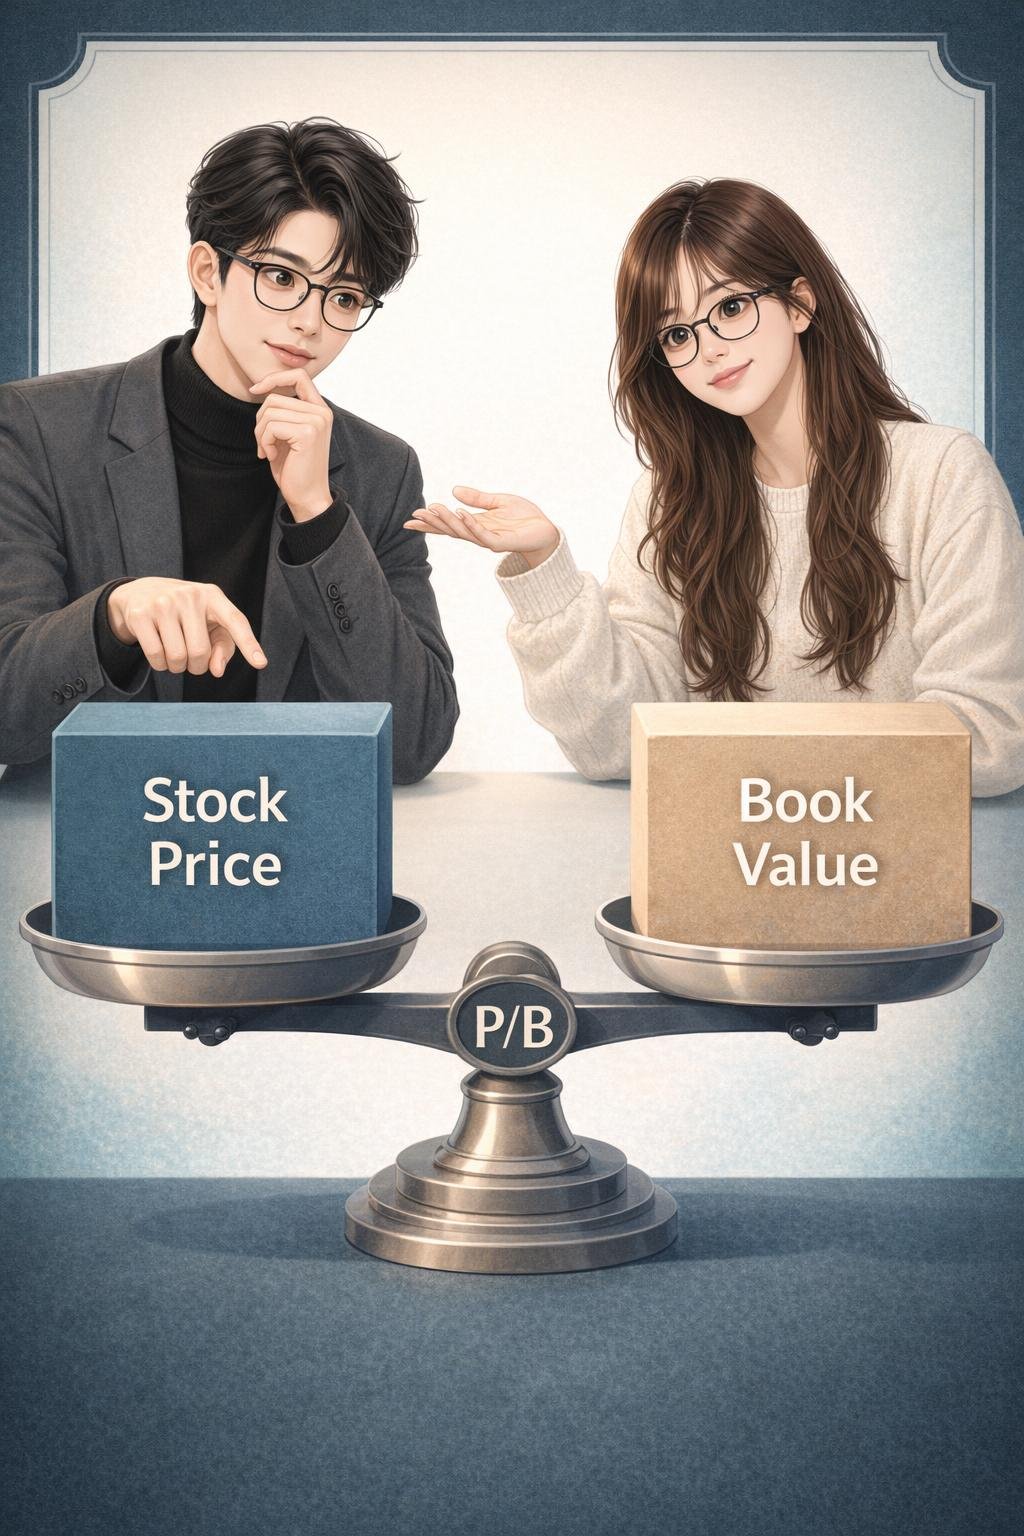
The P/B ratio expresses the relationship between a stock’s market price and the company’s book value on a per-share basis. A ratio of 1 means the stock price per share equals the reported book value per share. A ratio above 1 means the market price is higher than book value per share, while a ratio below 1 means the market price is lower.
These results need context. A high ratio may reflect market expectations, valuable assets that are not fully represented on the balance sheet, or other business characteristics. A low ratio may reflect concerns about the company’s assets, profitability, business prospects, or risks.
No single P/B value automatically proves that a stock is undervalued or overvalued. The ratio becomes more informative when it is compared with relevant peers and considered alongside other financial information.
Why the P/B Ratio Matters in Stock Valuation
Investors may encounter the P/B ratio as part of relative valuation. Relative valuation compares a company’s valuation multiple with the multiples of similar companies or with a relevant group benchmark.
Comparison is important because typical ratios can differ among industries and business models. Comparing two similar businesses may provide more useful context than comparing companies from unrelated industries.
The P/B ratio can be especially informative for asset-heavy businesses whose balance sheets contain substantial tangible assets. Tangible assets are physical or financial resources that can be identified in accounting records, such as property or equipment.
The ratio may be less informative for businesses whose value depends heavily on brands, internally developed intellectual property, knowledge, or other intangible resources that may not be fully reflected in book value. In those cases, the accounting value of net assets may provide an incomplete picture of the resources supporting the business.
How to Calculate the Price-to-Book Ratio

The formula is:
Price-to-book ratio = Current stock price per share ÷ Book value per share
- Current stock price per share is the market price of one share at the time the ratio is measured.
- Book value per share is the portion of the company’s reported book value assigned to each applicable share.
The result is a multiple. For example, a P/B ratio of 2 would mean the stock is priced at two times its book value per share. That description explains the arithmetic relationship but does not establish whether the stock is appropriately valued.
When real company data is used, the reporting period matters. Book value comes from financial statements for an identified period, while the stock price comes from a particular point in time. Readers should identify those dates and use relevant, reliable information rather than mixing figures from unrelated periods.
Hypothetical Price-to-Book Ratio Example
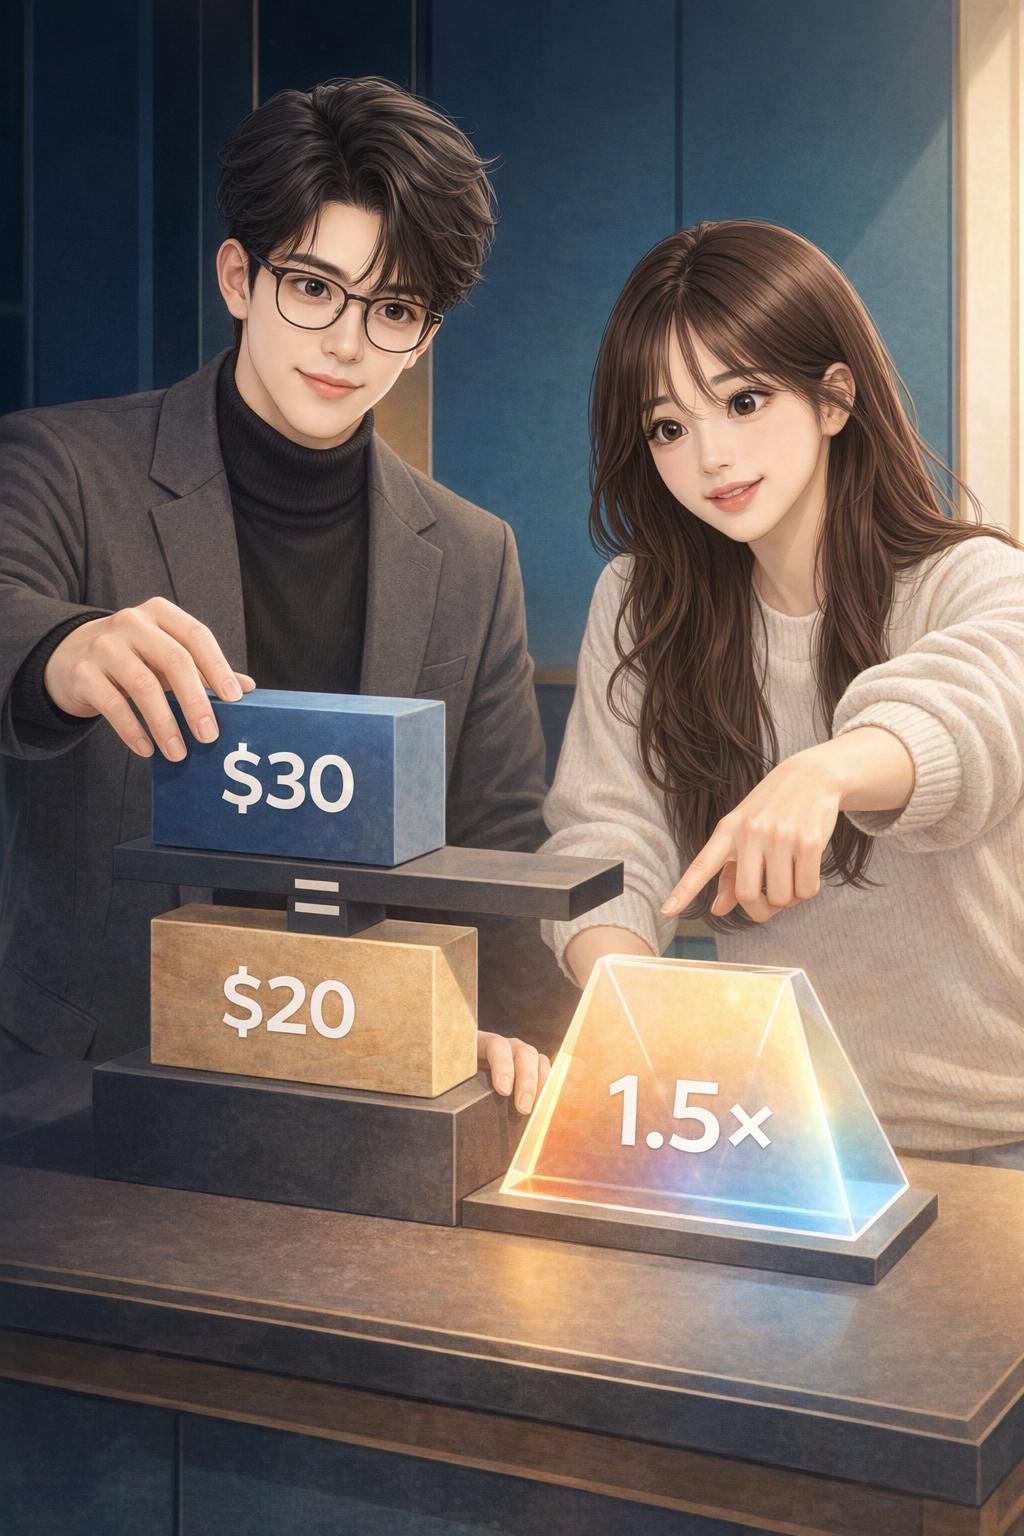
Hypothetical example: Assume a fictional company has a stock price of $30 per share and a book value of $20 per share. These invented figures are for education only and do not represent a real company.
The calculation would be:
$30 ÷ $20 = 1.5
The fictional company therefore has a P/B ratio of 1.5. This means its hypothetical stock price is one and a half times its hypothetical book value per share.
The result alone does not show whether the stock is undervalued, overvalued, or suitable for an investor. A useful interpretation would require information about comparable companies, the quality of the assets, the business model, financial performance, and relevant risks.
Related Concepts: Book Value and Relative Valuation
Book value
Book value generally refers to the accounting value remaining after a company’s reported liabilities are subtracted from its reported assets. It is closely related to shareholders’ equity on the balance sheet. Book value is an accounting measure, so it is not necessarily the amount shareholders would receive if the company sold all its assets.
Book value per share
Book value per share places book value on a per-share basis. In a simplified calculation, the relevant book value is divided by the applicable number of shares. Actual calculations may require attention to the company’s capital structure and the financial statement figures being used.
Relative valuation
Relative valuation evaluates a valuation multiple by comparing it with an appropriate benchmark. For a P/B comparison, that benchmark might be the ratio of a similar company or the average ratio for a group of comparable businesses.
Peer comparisons do not remove the need for analysis. Companies in the same industry may still have different asset quality, debt levels, profitability, risks, or accounting characteristics. Those differences help explain why similar companies can have different P/B ratios.
Common Misunderstandings and Limitations
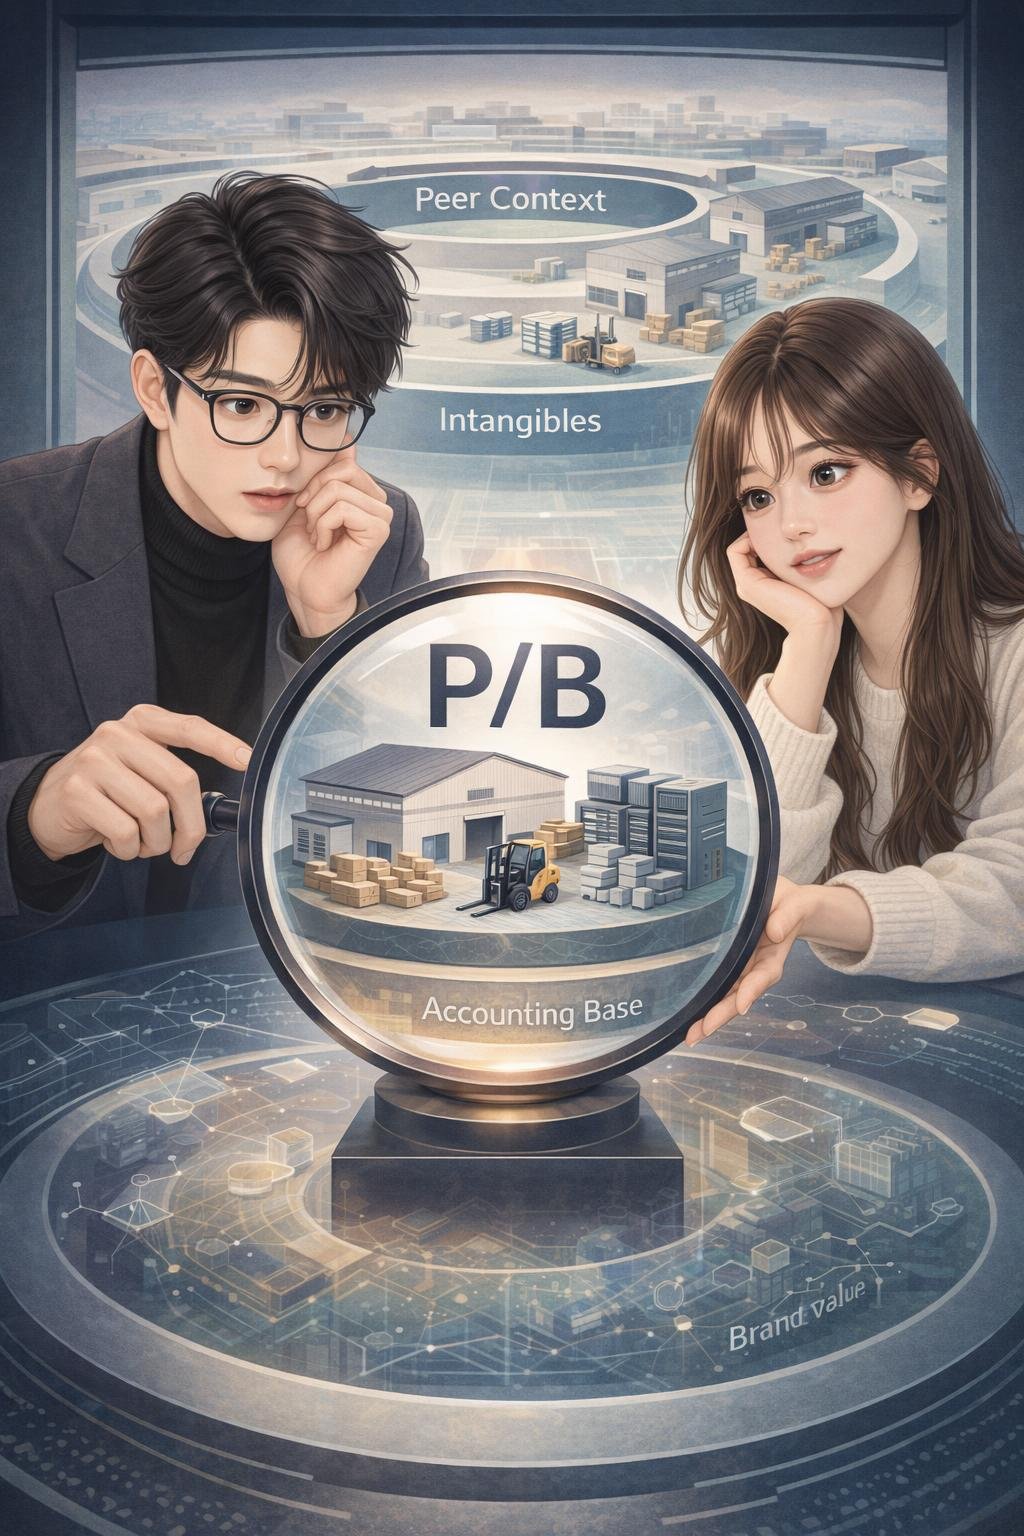
A P/B ratio below 1 does not automatically identify an undervalued stock. It means the market price per share is below the reported book value per share, but the market may be reflecting weakening business prospects, legal risks, concerns about asset values, or other problems.
Book value can also omit or underrepresent important intangible resources. A company may depend on its brand, intellectual property, software, workforce knowledge, or customer relationships even when those resources are not fully captured in reported book value. This can make P/B less useful for some business models.
The ratio also says little by itself about revenue, cash flow, profitability, debt obligations, management, competition, or future business conditions. It should therefore not be treated as a complete company valuation or as an automatic buy, sell, hold, or avoid signal.
Frequently Asked Questions About the P/B Ratio
Is a low P/B ratio always better?
No. A low ratio may appear inexpensive relative to reported book value, but it can also reflect concerns about the company’s assets, business prospects, profitability, or risks. The reason for the low ratio matters more than the number alone.
Can P/B ratios be compared across unrelated industries?
They can be placed side by side mathematically, but the comparison may not be meaningful. Industries differ in their use of tangible assets, intangible resources, financing, and accounting structures. Comparisons among similar businesses generally provide better context.
Why do intangible assets matter?
Intangible assets and resources can contribute significantly to a business even when their value is not fully included in book value. When these resources are central to a company’s operations, the denominator in the P/B ratio may not represent the full economic value associated with the business.
Can the P/B ratio determine an investment decision by itself?
No. The ratio measures one relationship between market price and accounting book value. An investment decision may also involve financial performance, cash flow, debt, asset quality, risks, business conditions, objectives, and personal risk tolerance.
Key Takeaway

The price-to-book ratio equals the current stock price per share divided by book value per share. It shows how the market price compares with an accounting measure of net assets on a per-share basis.
The ratio is most informative when it is compared with suitable peers and interpreted in light of the company’s industry, business model, assets, risks, reporting period, and other financial information. It is a comparison tool rather than a complete valuation or investment signal.
References
- Defining the Value of an Investment | Syndication
https://syndication.finra.org/content/defining-value-investment - Equity Valuation: Applications and Processes | CFA Institute
https://www.cfainstitute.org/insights/professional-learning/refresher-readings/2026/equity-valuation-applications-and-processesThis source supports the explanation of relative equity valuation and benchmark comparisons. It does not provide the article’s specific definition of the price-to-book ratio.
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.