
Cash Flow Statement: A Simple Definition
A cash flow statement is a financial statement that reports the cash entering and leaving a company during a specific period. It shows whether the company generated or used cash and explains how its cash balance changed.
The statement groups cash movements into three main categories: operating, investing, and financing activities. Together, these categories connect the company’s beginning cash balance with its ending cash balance.
What a Cash Flow Statement Means

Cash comes into a business when it collects money from customers, sells certain assets, borrows money, or receives funds from owners. Cash leaves when the business pays employees and suppliers, purchases assets, repays debt, or distributes money to owners.
A cash flow statement covers a defined reporting period. The period might be a quarter or a fiscal year, depending on the financial report. Readers should check the dates shown on the statement before comparing it with another period.
The statement reports changes in both cash and cash equivalents. Cash equivalents are highly liquid holdings that are treated much like cash because they can generally be converted into a known amount of cash quickly.
After all reported cash inflows and outflows are combined, the result explains the difference between beginning cash and ending cash. This reconciliation helps readers see why the company’s available cash increased or decreased during the period.
Why the Cash Flow Statement Matters to Investors
Investors encounter the cash flow statement as one of a company’s main financial statements. It provides information that is not always clear from reported revenue or profit alone.
The statement helps readers examine whether the company’s regular operations generated cash. It also shows how much cash the company used for investments and how borrowing, debt repayment, owner contributions, or distributions affected its cash position.
This information can help readers understand how a company supports its normal activities, purchases long-term assets, meets financial obligations, and obtains funding. Patterns across multiple reporting periods may offer more context than a single period.
A cash flow statement should not be used by itself to judge a company or an investment. Its figures are most useful when considered with the income statement, balance sheet, accompanying notes, reporting period, business model, and other relevant information.
How a Cash Flow Statement Works
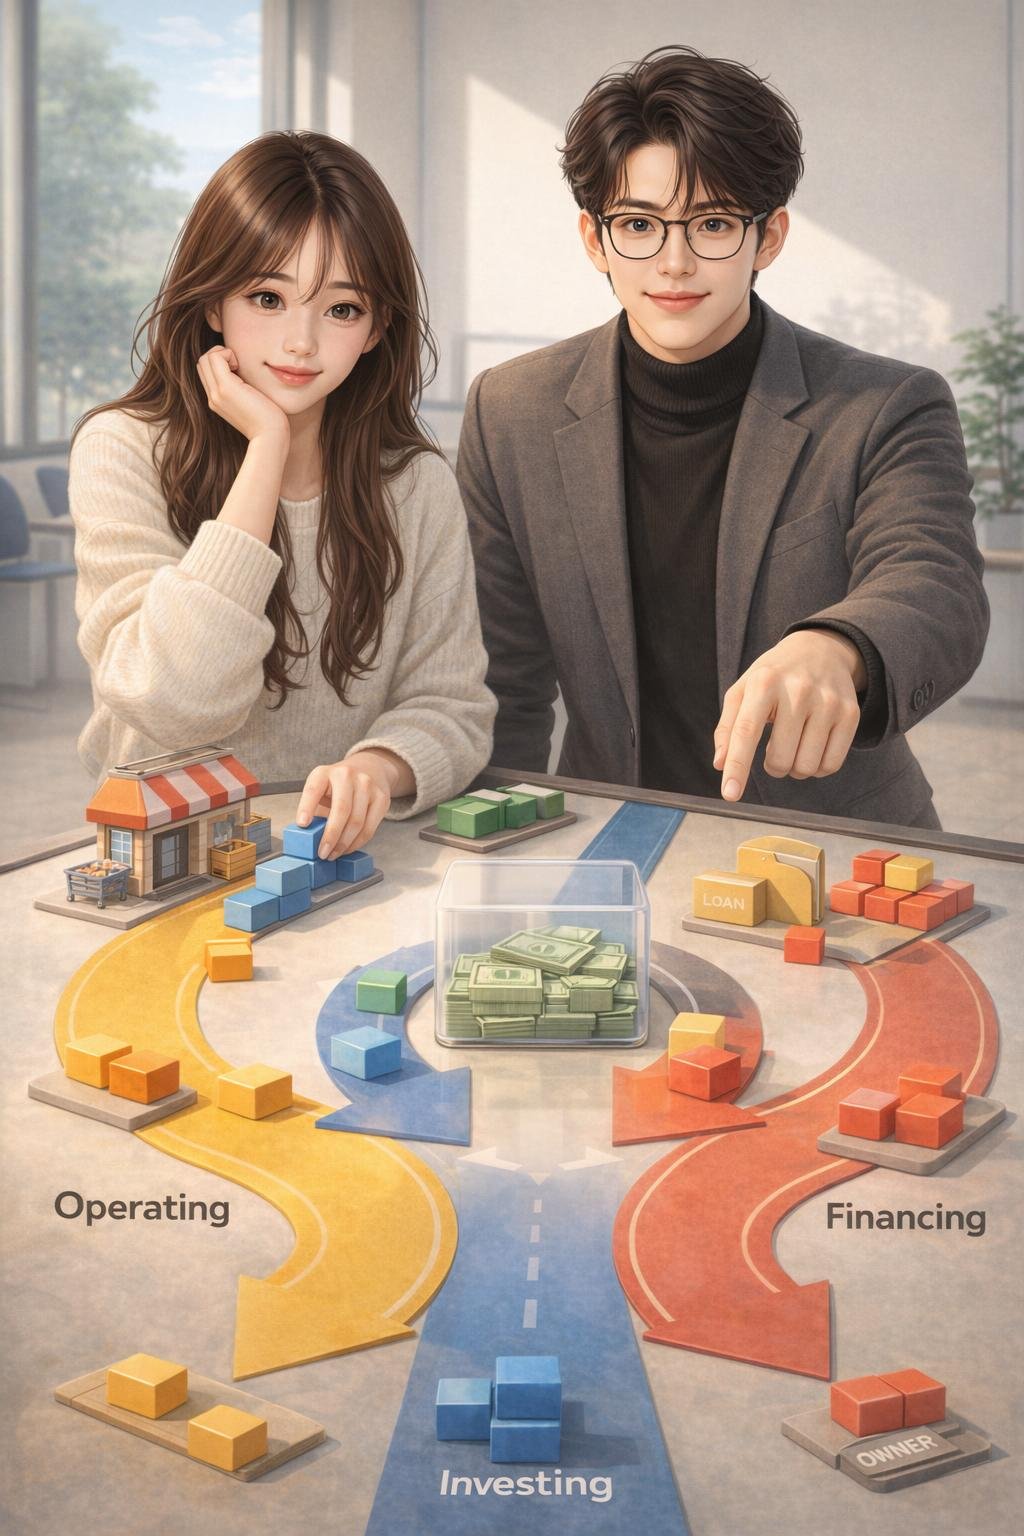
The cash flow statement starts with cash and cash equivalents at the beginning of a period. It then organizes the period’s cash movements into three classifications.
Operating activities
Operating activities generally reflect cash connected with the company’s main business operations. Examples include cash collected from customers and cash paid to employees or suppliers.
Investing activities
Investing activities generally show cash used for or received from investments in long-term resources. Examples include buying equipment or receiving cash from selling certain assets.
Financing activities
Financing activities generally show cash movements involving funding from creditors or owners. Examples include borrowing money, repaying debt, receiving owner contributions, or making distributions to owners.
The net cash amounts from all three classifications are combined to calculate the period’s overall change in cash. That change is added to or subtracted from beginning cash to arrive at ending cash.
Direct and indirect methods
The operating section may be presented using a direct or indirect method. The direct method displays major categories of operating cash receipts and payments, such as cash received from customers and cash paid to suppliers.
The indirect method begins with profit or loss and adjusts it for non-cash items, timing differences, and amounts associated with investing or financing activities. This process helps explain why reported profit and cash generated by operations are not necessarily equal.
Some investing and financing activities do not involve an immediate exchange of cash. These non-cash transactions are excluded from the cash flow statement itself, although they may be disclosed separately so readers can understand their financial effect.
Hypothetical Cash Flow Statement Example
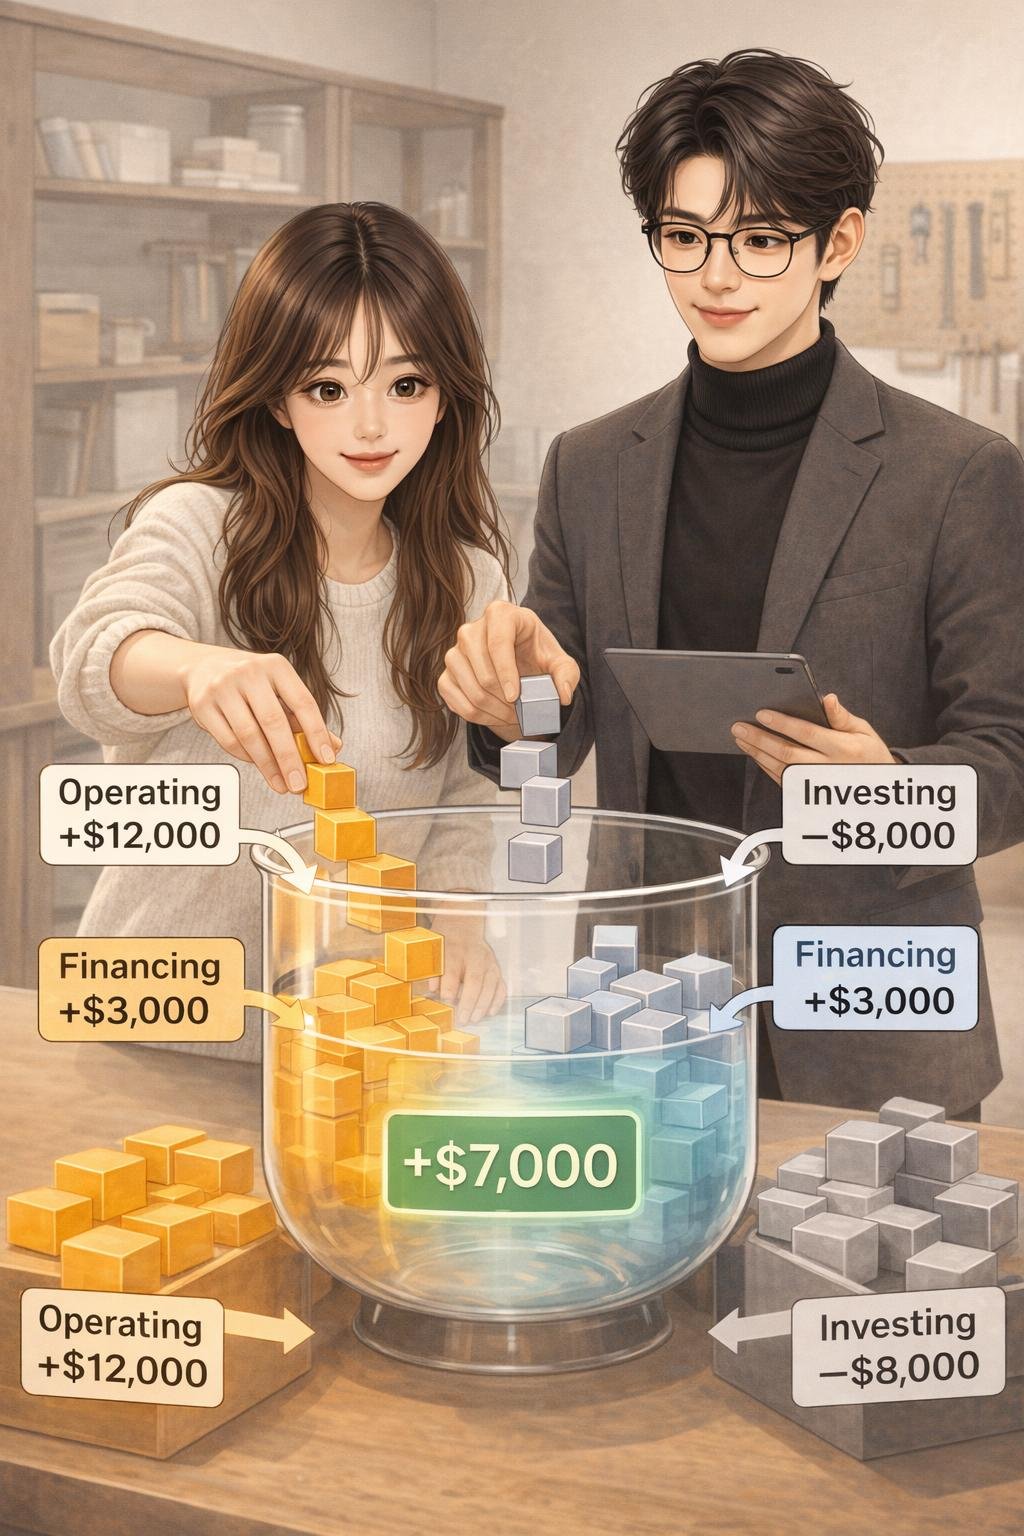
Educational hypothetical example: The following invented amounts describe a fictional business. They are not financial data from a real company.
| Cash flow category | Hypothetical amount |
|---|---|
| Net cash from operating activities | $12,000 |
| Net cash used in investing activities | -$8,000 |
| Net cash from financing activities | $3,000 |
| Net increase in cash | $7,000 |
In this example, the fictional business generated $12,000 of cash from its operations. It used $8,000 for investing activities and received a net $3,000 from financing activities.
Combining the three sections gives a $7,000 net increase in cash: $12,000 minus $8,000 plus $3,000 equals $7,000.
| Cash reconciliation | Hypothetical amount |
|---|---|
| Beginning cash and cash equivalents | $20,000 |
| Net increase in cash | $7,000 |
| Ending cash and cash equivalents | $27,000 |
The example shows how the operating, investing, and financing sections explain the movement from $20,000 of beginning cash to $27,000 of ending cash.
Related Financial Statement Concepts
Cash and cash equivalents
Cash includes money available for use. Cash equivalents are highly liquid holdings treated similarly to cash for financial reporting purposes. The exact components should be reviewed in the company’s financial statements and notes.
Operating cash flow
Operating cash flow is the net cash provided by or used in the company’s main operating activities. It helps show how routine business activity affected cash during the period.
Investing cash flow
Investing cash flow is the net cash associated with activities such as acquiring or disposing of long-term assets and certain investments. Negative investing cash flow may reflect purchases of assets, but its meaning depends on the details and context.
Financing cash flow
Financing cash flow is the net cash associated with obtaining or returning capital. It can include borrowing, repaying debt, owner contributions, share-related transactions, or distributions, depending on the company and reporting framework.
Net income
Net income is an accounting measure of profit reported on the income statement. It includes recognized revenue and expenses, which do not always involve cash entering or leaving during the same period.
Non-cash items
Non-cash items affect reported profit or financial position without creating an immediate cash receipt or payment. Under the indirect method, certain non-cash items are adjustments used to reconcile net income with operating cash flow.
Income statement
The income statement reports revenue, expenses, and profit or loss over a period. The cash flow statement focuses instead on cash movements. Comparing the two can help explain why profit and operating cash flow differ.
Balance sheet
The balance sheet reports a company’s assets, liabilities, and owners’ equity at a particular date. Its cash balance connects with the ending cash reported in the cash flow statement, subject to the classifications and reconciliations disclosed in the financial statements.
Together, the income statement, balance sheet, cash flow statement, and related notes provide different views of the same business. No single statement gives a complete picture on its own.
Common Cash Flow Statement Misunderstandings
Cash flow is not the same as profit
A company can report profit while using cash, or report a loss while generating cash during a particular period. Timing differences and non-cash accounting items can cause net income and cash flow to differ.
Positive cash flow does not automatically make an investment attractive
Positive total cash flow only means that cash increased during the period. The increase might have come from operations, asset sales, borrowing, or owner financing. Its source and sustainability require further context.
Negative cash flow does not automatically mean failure
Negative cash flow means that cash decreased during the period. A company might use cash to purchase long-term assets, repay debt, or support operations. Readers need to examine why the cash was used and whether the situation is manageable.
One period may not reveal a lasting pattern
A single reporting period can be affected by timing, unusual transactions, seasonal activity, or major asset purchases. Reviewing several comparable periods can provide more context.
One section cannot explain the whole statement
Strong operating cash flow can appear alongside substantial investing or financing outflows. Likewise, an increase in total cash can occur even when operations use cash if financing provides enough additional funds. All three sections should be considered together.
Cash Flow Statement FAQ
Where can I find a company’s cash flow statement?
It generally appears with the other financial statements in a company’s periodic financial reports. Readers should confirm the reporting period and consult the accompanying notes for definitions and additional details.
How is a cash flow statement different from an income statement?
An income statement reports recognized revenue, expenses, and profit or loss. A cash flow statement reports cash inflows and outflows. Accounting recognition and cash payment timing can differ, so the statements answer different questions.
What does positive cash flow mean?
Positive net cash flow means cash and cash equivalents increased during the period. It does not explain the cause by itself. Readers must examine whether the increase came from operating, investing, or financing activities.
What does negative cash flow mean?
Negative net cash flow means cash and cash equivalents decreased during the period. The significance depends on the reason, the company’s available resources, its obligations, and whether the change is temporary or part of a broader pattern.
Why can net income differ from operating cash flow?
Net income follows accounting recognition rules and can include non-cash expenses or amounts not yet collected or paid. Operating cash flow adjusts for relevant non-cash items and timing differences to focus on cash connected with operations.
Should investors examine all three cash flow sections?
Yes. Operating activities show cash connected with the main business, investing activities show cash associated with long-term resources and investments, and financing activities show how the company obtains or returns capital. Their relationship provides more context than any section viewed alone.
Key Takeaway

A cash flow statement explains how a company’s cash and cash equivalents changed during a reporting period. It organizes cash movements into operating, investing, and financing activities and reconciles beginning cash with ending cash.
The statement is most useful when readers examine the source and use of cash, compare appropriate reporting periods, and consider the results alongside the income statement, balance sheet, notes, and other relevant context.
References
- Title: https://www.investor.gov/introduction-investing/investing-basics/glossary/cash-flow-statement
URL: https://www.investor.gov/introduction-investing/investing-basics/glossary/cash-flow-statement - Title: https://www.investor.gov/introduction-investing/investing-basics/glossary/cash-flow-statement-1
URL: https://www.investor.gov/introduction-investing/investing-basics/glossary/cash-flow-statement-1 - Title: IFRS – IAS 7 Statement of Cash Flows
URL: https://www.ifrs.org/issued-standards/list-of-standards/ias-7-statement-of-cash-flows.html/
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.