
Operating Margin: A Plain-Language Definition
Operating margin is the percentage of sales a company retains as operating profit after paying the expenses associated with running its core business. It shows how much profit the company’s main operations generate before considering non-operating sources of profit.
What Operating Margin Means
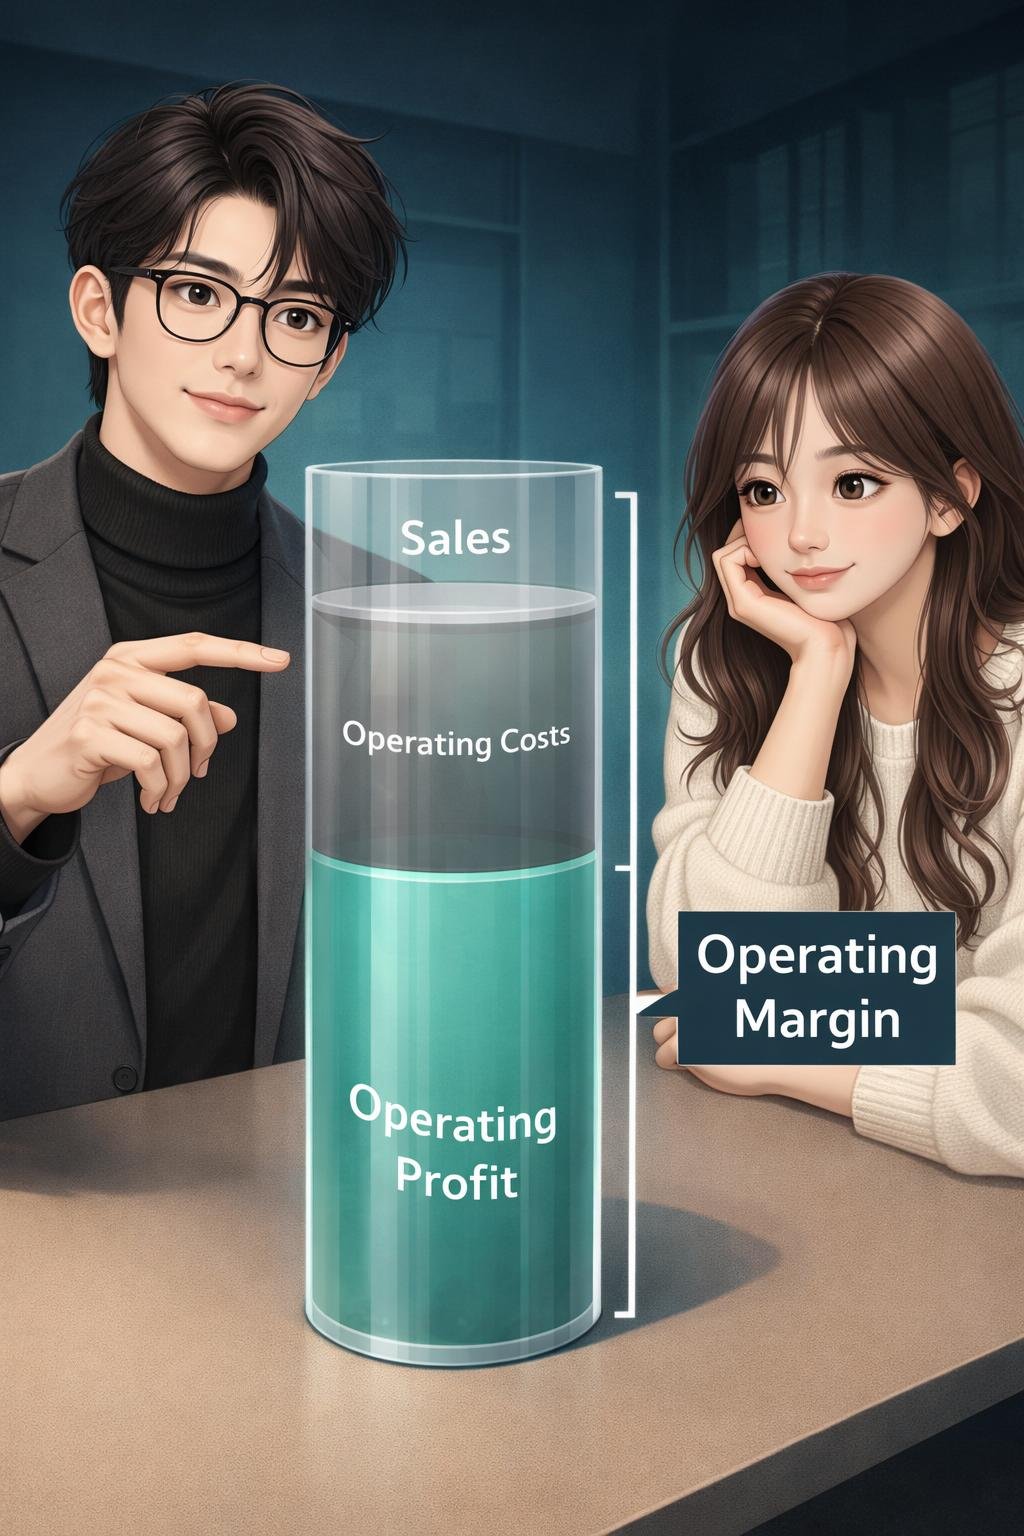
Operating margin translates a company’s operating profit into a percentage of its sales. Sales are the amounts earned from providing goods or services before related expenses are deducted.
Operating expenses are the costs associated with producing and selling those goods or services and running the business. They include the cost of goods sold and other operating expenses.
For example, an operating margin of 20% means that the company generated 20 cents of operating profit for every dollar of sales during the relevant reporting period. The remaining 80 cents went toward the operating costs included in the calculation.
Why Operating Margin Matters
Operating margin commonly appears in financial analysis because it helps readers understand how much operating profit a business generates from its sales. It puts operating profit and sales into a single ratio that can be easier to interpret than a dollar amount alone.
The ratio may also help readers examine changes in a company’s operating performance across comparable reporting periods. A change can result from movements in sales, the cost of goods sold, other operating expenses, or a combination of these factors.
Operating margin is only one analytical measure. It does not, by itself, show whether a security is suitable for an investor or predict the company’s future results.
How to Calculate Operating Margin
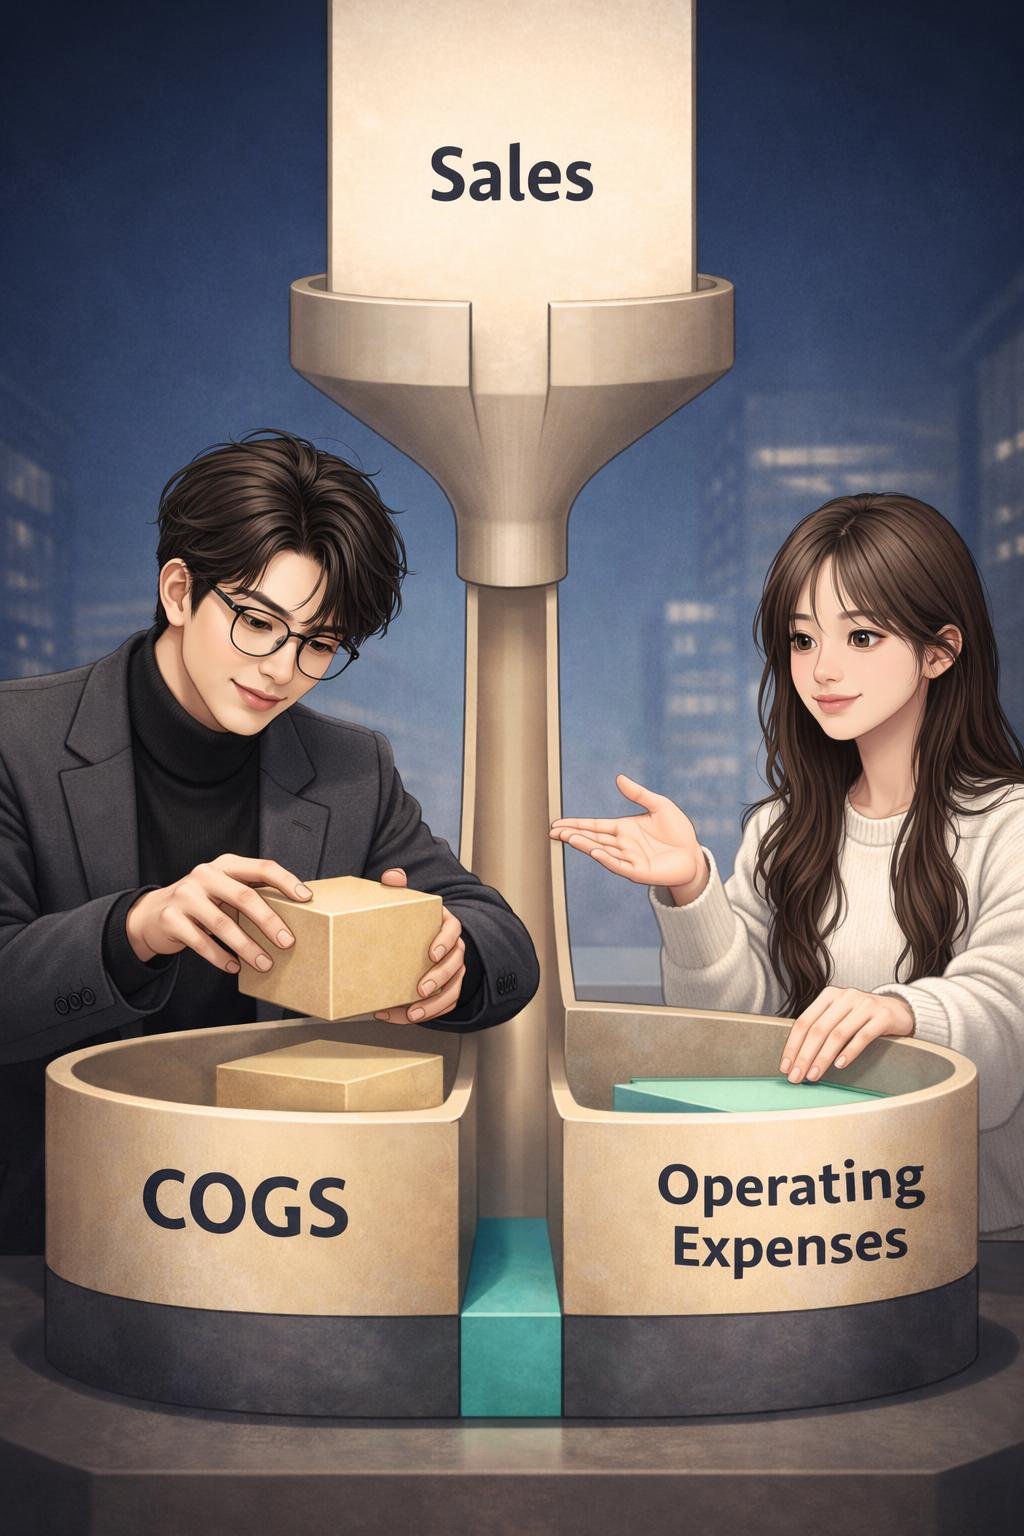
The supported formula is:
Operating margin = (Sales − Cost of Goods Sold − Other Operating Expenses) / Sales
The components mean:
- Sales: The amount generated from selling goods or services during the reporting period.
- Cost of goods sold: The costs attributed to the goods or services sold.
- Other operating expenses: Additional expenses associated with operating the business.
Subtracting the cost of goods sold and other operating expenses from sales produces operating profit. Dividing that operating profit by sales produces a decimal. Multiplying the decimal by 100 expresses the result as a percentage.
A larger percentage means more operating profit was generated from each dollar of sales for the period being measured. A smaller percentage means less operating profit was generated from each sales dollar. There is no universal percentage that is automatically good or bad because business models and cost structures can differ.
Hypothetical Operating Margin Example
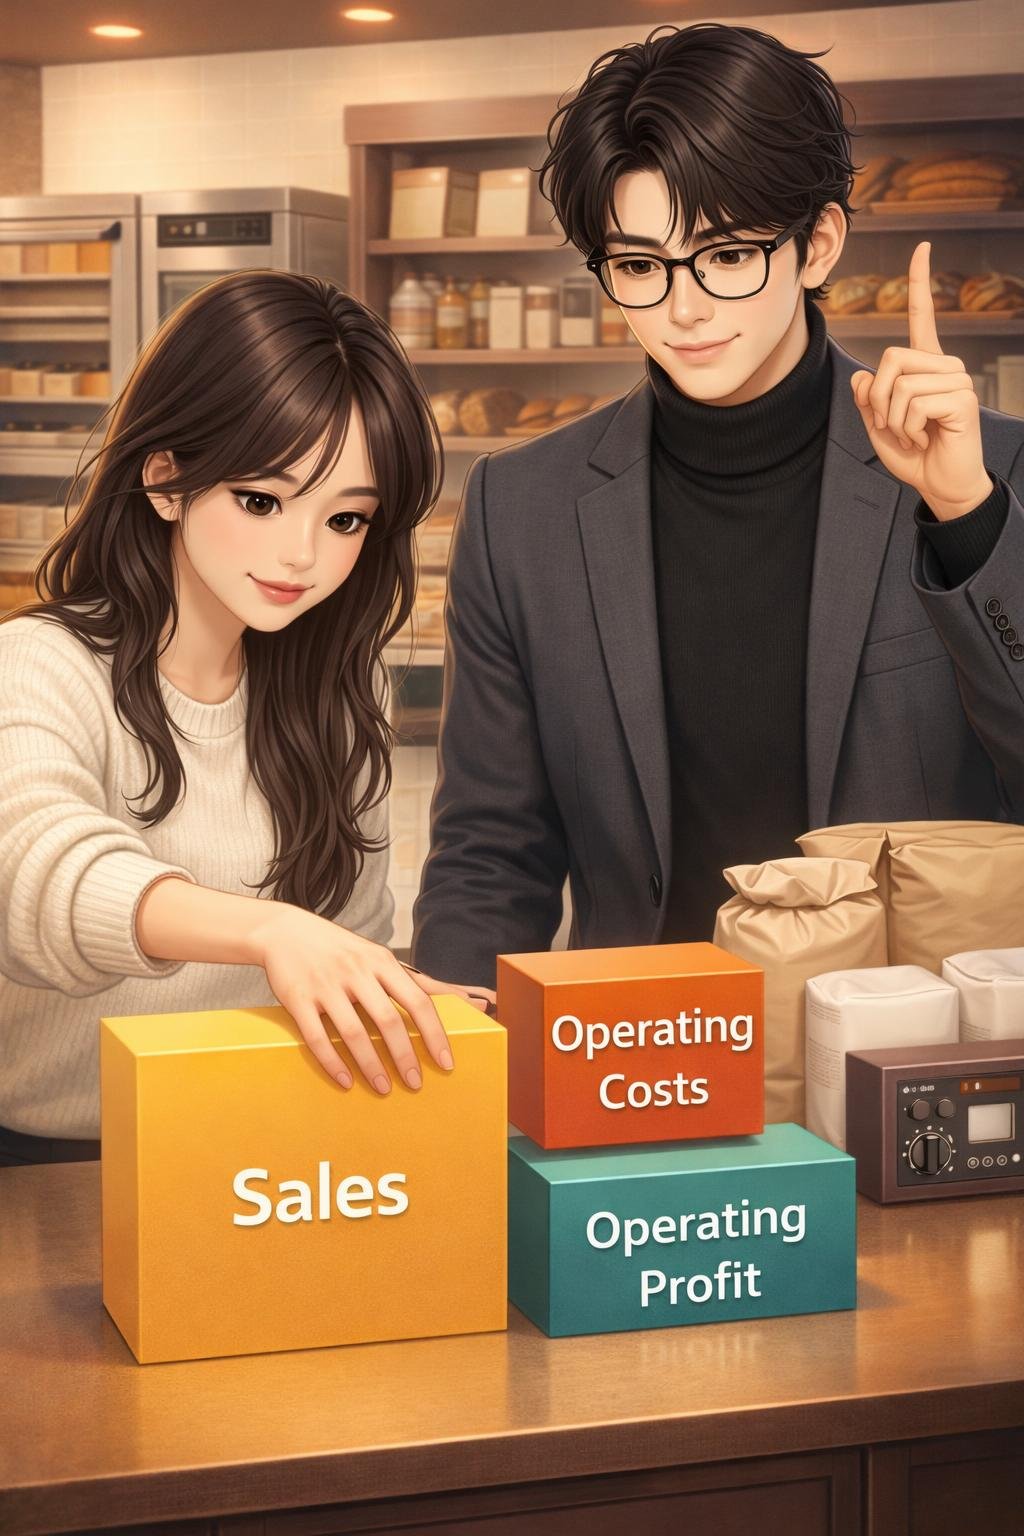
Hypothetical example: The following invented figures are for illustration only and do not represent a real company.
- Sales: $100,000
- Cost of goods sold: $60,000
- Other operating expenses: $20,000
First, calculate operating profit:
$100,000 − $60,000 − $20,000 = $20,000
Next, divide operating profit by sales:
$20,000 / $100,000 = 0.20
Finally, multiply the decimal by 100:
0.20 × 100 = 20%
The hypothetical company therefore has a 20% operating margin. In plain language, it generated 20 cents of operating profit for every dollar of sales after paying the operating expenses included in the calculation.
Operating Margin and Related Profit Measures
Sales are the starting point for the calculation. Subtracting the cost of goods sold and other operating expenses from sales produces operating profit. Operating margin then compares that operating profit with sales.
This relationship is useful because operating profit is a dollar amount, while operating margin is a percentage. The percentage provides context by showing the amount of operating profit generated relative to the size of the company’s sales.
Operating margin focuses on core business operations. It does not attempt to represent profit from non-operating sources, such as investing activities. Readers should therefore avoid treating operating margin as a measure of every possible source of company profit.
Common Operating Margin Misunderstandings
- It is a percentage, not a dollar amount. Operating profit is expressed in currency, while operating margin expresses operating profit as a share of sales.
- It does not represent every source of profit. The ratio focuses on operating activities rather than non-operating sources.
- A higher margin is not automatically better in every comparison. Differences in business models, costs, and reporting periods can affect the result.
- It is not proof that a security is attractive. One ratio cannot capture every factor relevant to a company or an investment decision.
- It does not guarantee future performance. Sales and expenses can change, so a historical operating margin does not assure the same result in a future period.
Operating Margin FAQs
Where do the figures used in the calculation come from?
The inputs come from a company’s financial information. Readers should use figures for the same reporting period and verify them through official company reports, filings, or investor-relations materials when analyzing a real business.
Can operating margin change?
Yes. Operating margin can change when sales, the cost of goods sold, or other operating expenses change. The reason for a change cannot be determined from the percentage alone, so the underlying figures also matter.
Is a higher operating margin always better?
Not necessarily. A higher figure means more operating profit was generated per dollar of sales during the measured period, but it does not provide a complete assessment of the company. Meaningful interpretation requires context, including the company’s business model and the periods being compared.
Why does the reporting period matter?
Sales and expenses relate to a specific period. Comparing figures from different or mismatched periods can produce a misleading result. Readers should identify the relevant reporting period before calculating or comparing operating margins.
Can operating margin be used alone to make an investment decision?
No single ratio provides a complete view of a company or security. Operating margin can contribute to financial analysis, but it is not a stand-alone basis for deciding whether to buy, sell, hold, or avoid an investment.
Key Takeaway
Operating margin is the percentage of sales remaining as operating profit after the cost of goods sold and other operating expenses are deducted. It helps explain how much operating profit a company generates from its core activities, but it should be considered alongside other information rather than used as a stand-alone basis for an investment decision.
References
- How to Use Profitability & Margin Ratios — https://online.hbs.edu/blog/post/margin-ratios
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.