
What Is Return on Assets (ROA)?
Return on assets (ROA) is a financial measure that shows how efficiently a company generates profit from its assets. It compares the company’s net income with the resources it uses in its business.
ROA is usually expressed as a percentage. It helps explain how much net income a company generates for each dollar of assets.
What ROA Means
ROA connects two parts of a company’s financial information: net income and assets. Net income is the profit remaining after expenses. Assets are resources owned or controlled by the company, such as cash, inventory, property, equipment, and investments.
For example, an ROA of 8% means the company generated 8 cents of net income for each dollar of assets included in the calculation. The percentage describes asset efficiency, but it does not explain every aspect of the company’s financial condition.
Why ROA Matters in Company Analysis
ROA can help readers examine how effectively a company uses its assets to produce net income. A change in ROA over time may show that the relationship between profit and assets has changed.
Readers can compare a company’s ROA across multiple reporting periods. To make the comparison meaningful, they should check that the figures cover comparable periods and use a consistent calculation method.
ROA can also be used to compare competitors. However, appropriate ROA levels vary by industry because different types of businesses use different amounts and kinds of assets. Comparisons are generally more informative when the companies have similar operations.
How to Calculate ROA
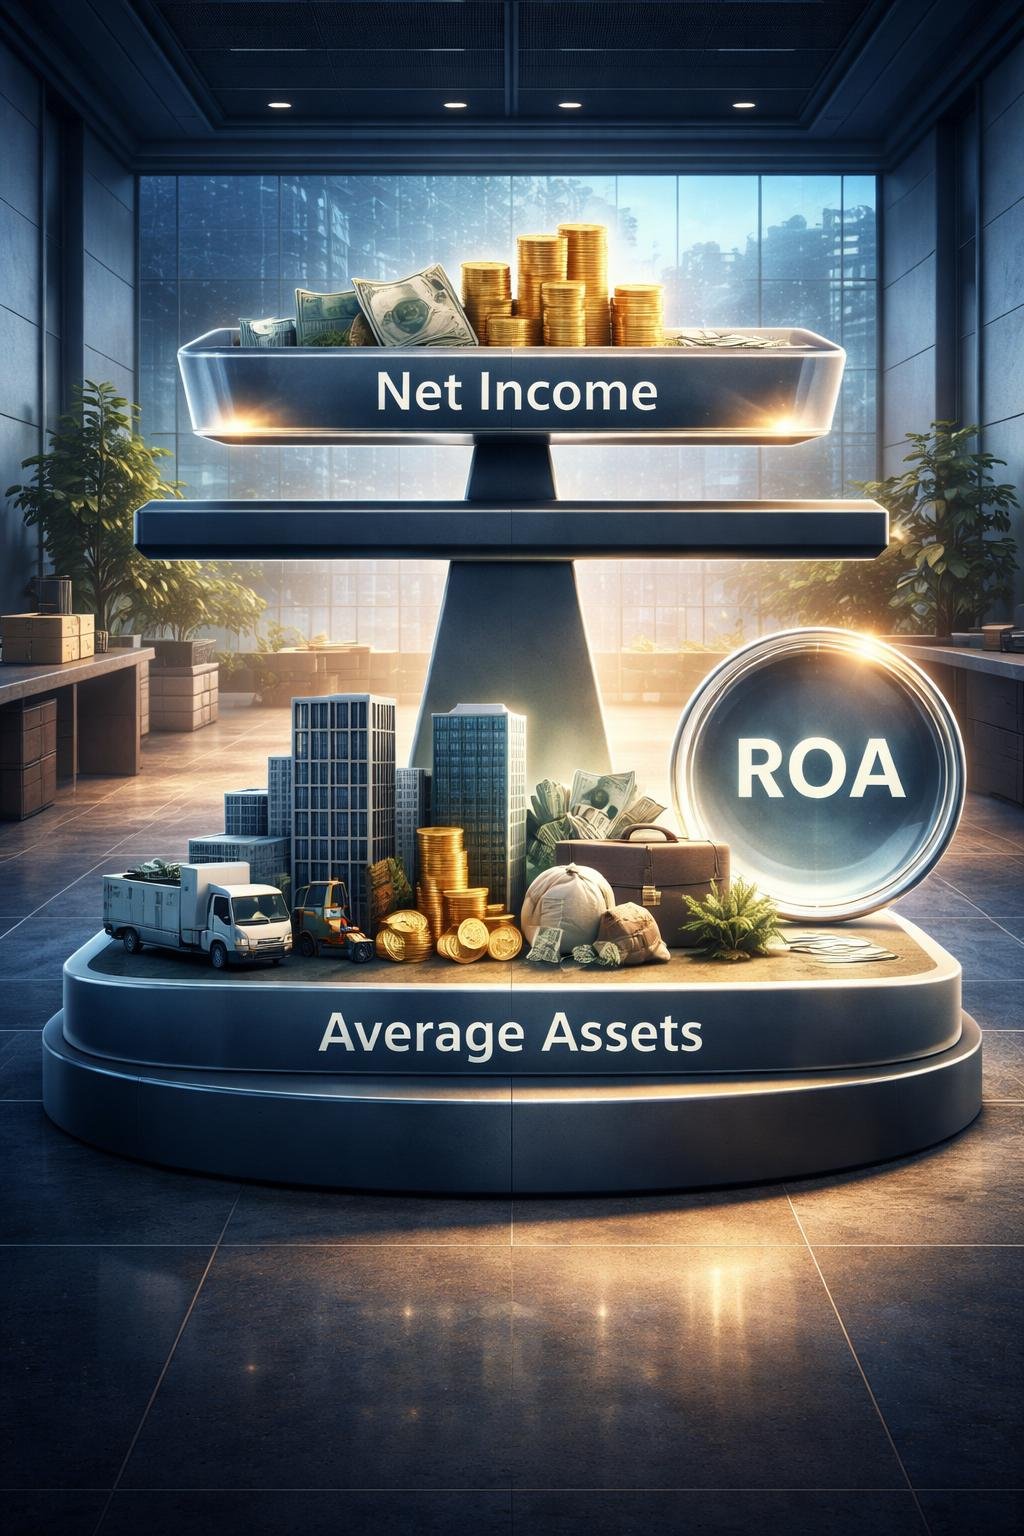
The basic formula is:
ROA = Net income ÷ Assets
To express the result as a percentage, multiply the decimal result by 100:
ROA percentage = (Net income ÷ Assets) × 100
Net income is the company’s profit after expenses. Assets include resources such as cash, inventory, property, equipment, and investments.
The denominator may use total assets reported at the end of a period. Another approach uses average yearly assets, which accounts for the asset balance at both the beginning and end of the year:
Average yearly assets = (Beginning-of-year assets + End-of-year assets) ÷ 2
Average assets may provide a more accurate denominator because net income covers activity over a period, while a period-end asset figure represents one point in time.
Hypothetical ROA Calculation Example
Hypothetical example: Assume an imaginary company reports $50,000 in net income and has $500,000 in assets. These invented figures do not belong to a real company.
- Divide net income by assets: $50,000 ÷ $500,000 = 0.10.
- Multiply the result by 100 to express it as a percentage: 0.10 × 100 = 10%.
The hypothetical company’s ROA is 10%. This means it generated 10 cents of net income for each dollar of assets included in the calculation.
Key Financial Terms Used in ROA
Net income
Net income is the profit remaining after a company accounts for its expenses. It is the numerator, or top part, of the ROA formula.
Total assets
Total assets are the resources included on a company’s balance sheet. Examples can include cash, inventory, property, equipment, and investments. Total assets form the denominator, or bottom part, of the basic ROA formula.
Average assets
Average assets are calculated by adding the asset balance at the beginning of a period to the balance at the end of the period and dividing the total by two. This approach reflects both points in time rather than relying only on the ending balance.
Common ROA Misunderstandings
- A higher or lower ROA should not be judged in isolation. The percentage needs context, including the company’s earlier results and the results of comparable businesses.
- ROA levels are not directly comparable across every industry. Industries can differ in the types and amounts of assets companies need to operate.
- Not every ROA calculation uses the same denominator. One calculation may use period-end total assets, while another may use average assets. Readers should check the method before comparing results.
- ROA does not determine whether a security is suitable for an investor. It is one financial measure and does not account for an investor’s circumstances, objectives, or risk tolerance.
Frequently Asked Questions About ROA
How should I interpret an ROA percentage?
The percentage shows the amount of net income generated per dollar of assets. For example, a 5% ROA represents 5 cents of net income for each dollar of assets used in the calculation.
Can ROA be compared across companies?
Yes, but the comparison requires context. It is more useful when companies operate in similar industries and the calculations cover comparable periods and use the same type of asset denominator.
Why are average assets sometimes used?
Net income measures activity over a period, while ending assets represent a single date. Average assets incorporate both beginning and ending balances, which may provide a more representative denominator for the period.
Should ROA be considered by itself?
No. ROA addresses the relationship between net income and assets, but it does not provide a complete assessment of a company or determine whether a security fits an investor’s needs.
Key Takeaway
Return on assets measures how efficiently a company generates net income from its assets. It is calculated by dividing net income by assets and is commonly expressed as a percentage. ROA can support comparisons over time and among competitors, but readers should account for the reporting periods, calculation methods, and industry differences involved.
References
- The Return on Assets (ROA) Formula Explained — https://online.hbs.edu/blog/post/return-on-assets
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product.
Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.