
Working Capital: A Plain-Language Definition
Working capital is the difference between a company’s current assets and current liabilities. It is also called net working capital.
The figure helps show whether a company has enough short-term resources to cover short-term obligations and support daily operations. It is a financial measure, not a separate bank account or pile of cash.
What Working Capital Means
Current assets are short-term resources shown on a company’s balance sheet. They may include cash, amounts customers owe the company, and inventory intended for sale.
Current liabilities are obligations the company expects to pay in the short term. Examples may include amounts owed to suppliers, accrued expenses, and certain short-term debt.
The relationship between these two totals produces one of three basic results:
- Positive working capital: Current assets are greater than current liabilities.
- Zero working capital: Current assets equal current liabilities.
- Negative working capital: Current liabilities are greater than current assets.
These results describe a mathematical relationship. A positive figure is not automatically proof that a company is financially strong, and a negative figure does not provide a complete judgment by itself.
Why Working Capital Matters in Company Analysis
Investors and business analysts examine working capital because companies need short-term resources to pay suppliers, meet payroll, maintain inventory, and handle other daily expenses.
Working capital can also provide information about operational efficiency, meaning how effectively a company manages resources and obligations connected with its normal business activities. For example, slow customer payments or unsold inventory can affect the quality and availability of current assets.
The measure can indicate short-term financial health because it compares resources available in the short term with obligations due in the short term. However, the meaning depends on the company’s business model, operating cycle, asset composition, and changes over time.
How to Calculate Working Capital
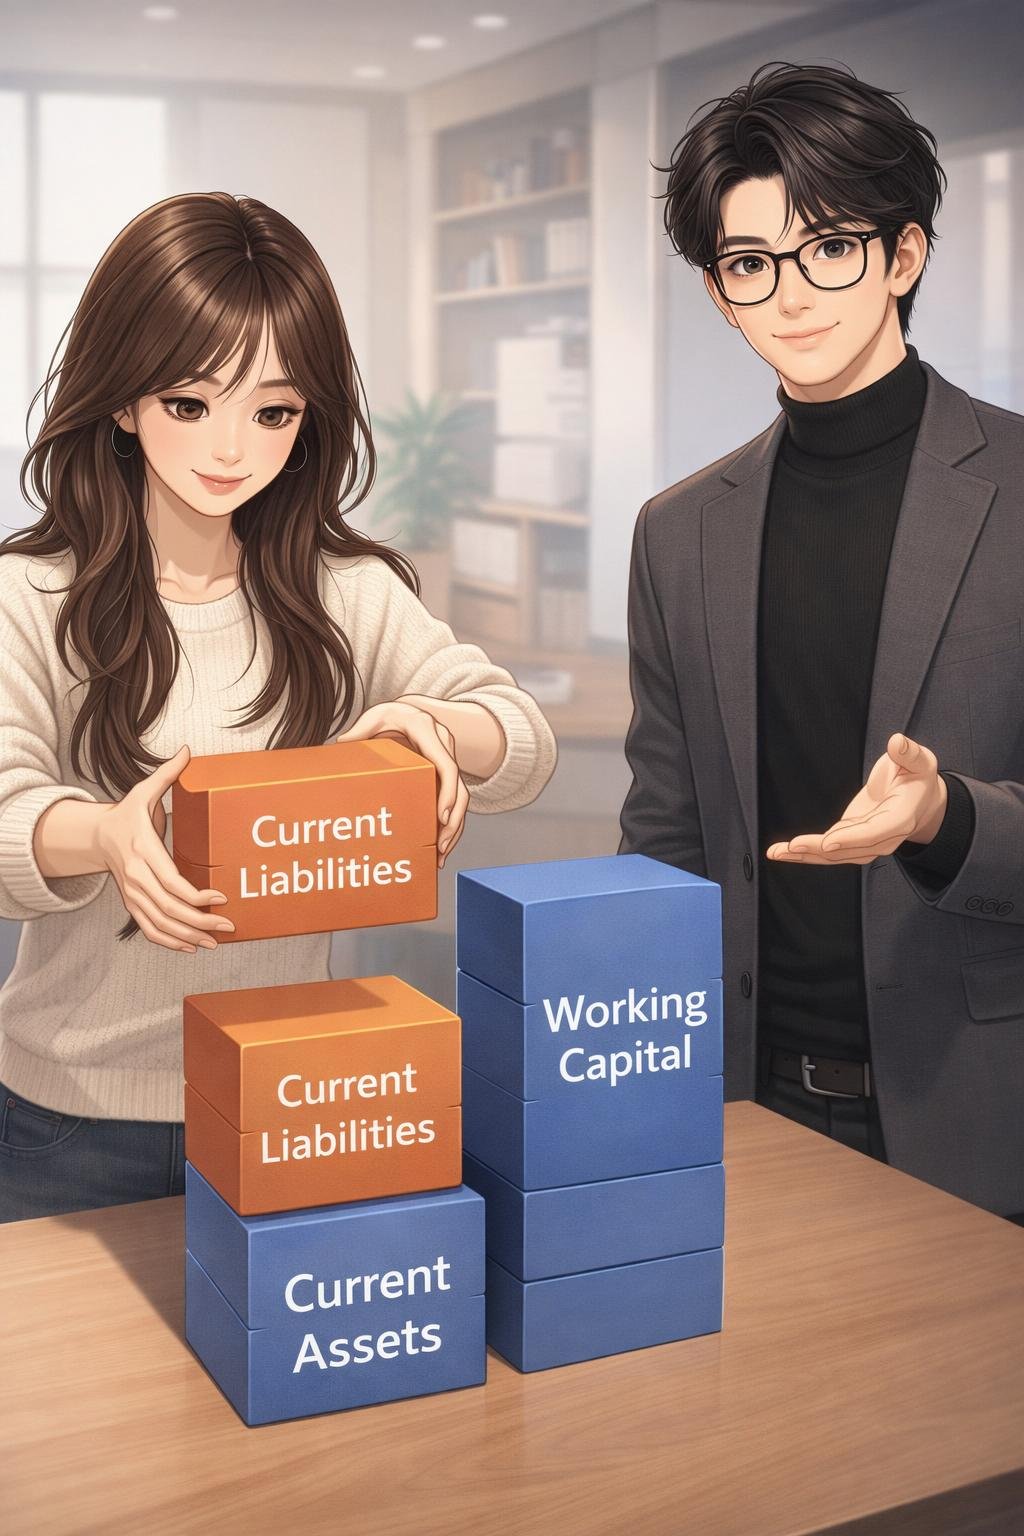
The basic formula is:
Working capital = Current assets − Current liabilities
An increase in current assets raises working capital if current liabilities remain unchanged. An increase in current liabilities lowers working capital if current assets remain unchanged.
The calculation uses totals reported for the same balance-sheet date. When analyzing a real company, readers should check the relevant financial statements and identify the reporting period because account balances can change.
Hypothetical Working Capital Example
Hypothetical example: The following figures are invented for educational purposes and do not represent a real company.
Suppose a fictional company reports $120,000 in current assets and $75,000 in current liabilities.
- Start with current assets of $120,000.
- Subtract current liabilities of $75,000.
- The calculation is $120,000 − $75,000 = $45,000.
The fictional company therefore has positive working capital of $45,000. This means its current assets exceed its current liabilities by $45,000 on the measurement date. It does not mean that the company necessarily has $45,000 in cash, because current assets may also include inventory and amounts owed by customers.
Related Concepts to Understand
- Net working capital: This is another name commonly used for working capital. Both terms generally refer to current assets minus current liabilities.
- Current assets: These form the resource side of the calculation. Their composition matters because cash, customer receivables, and inventory do not have the same level of immediate availability.
- Current liabilities: These form the obligation side of the calculation and represent short-term amounts the company must pay or settle.
- Daily operations: Companies use short-term resources to support routine activities such as paying employees, purchasing supplies, and fulfilling customer orders.
- Operational efficiency: Working capital may offer clues about how a company manages inventory, collects customer payments, and pays suppliers.
- Short-term financial health: The figure helps compare short-term resources with short-term obligations, but it does not measure every financial strength or risk.
These concepts are connected because the type, timing, and management of current assets and current liabilities affect whether working capital can effectively support daily operations.
Common Working Capital Misunderstandings
Working capital is not the same as current assets. It is the amount remaining after current liabilities are subtracted from current assets.
It is also not a single account balance. The figure combines multiple balance-sheet accounts into one difference.
Finally, working capital is not a complete company analysis. Analysts may also examine cash flow, debt, profitability, asset quality, business conditions, and trends across multiple reporting periods before forming a broader view.
Frequently Asked Questions About Working Capital
Are working capital and net working capital the same thing?
They generally mean the same thing: current assets minus current liabilities. A company or analyst may define a specialized version differently, so readers should check the stated formula when one is provided.
Can working capital be negative?
Yes. Working capital is negative when current liabilities exceed current assets. This result may signal short-term financial pressure, but its significance depends on the company’s operations, cash flows, payment timing, and industry characteristics.
Does positive working capital mean the company has plenty of cash?
No. Current assets may include inventory and amounts owed by customers. Positive working capital therefore does not show how much cash is immediately available.
Why should working capital be part of a broader analysis?
Working capital focuses on short-term assets and liabilities. It does not by itself explain profitability, long-term debt, cash generation, competitive position, or the quality of individual assets, so it should be interpreted alongside other company information.
Key Takeaway
Working capital equals current assets minus current liabilities. It is a useful indicator of the short-term resources available to support daily operations and meet short-term obligations. However, it is only one part of company analysis and should not be treated as a complete measure of financial condition.
References
- Financial Terminology: 20 Financial Terms to Know — https://online.hbs.edu/blog/post/finance-for-non-finance-professionals-finance-terms-to-know.
This source supports the general definition and purpose of working capital described in this article.
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.