
Enterprise Value: A Plain-Language Definition
Enterprise value, commonly abbreviated as EV, is an estimate of the total market value of a company’s operating business. It looks beyond the value of the company’s common shares by accounting for debt, cash, and other relevant ownership interests.
Market capitalization measures only the market value of common equity. Enterprise value takes a broader view by considering the claims of multiple groups that provide capital to the business.
What Enterprise Value Means
A company can finance its operations with common equity, debt, preferred equity, or a combination of these sources. Enterprise value attempts to bring these financing claims together in one company-wide measure.
Debt is generally added because lenders have a financial claim on the business. Preferred equity may also be added because preferred shareholders have a claim that is separate from common shareholders.
Minority interests, also called noncontrolling interests, may be included when a company reports the full financial results of a subsidiary that it does not own completely. Adding the minority interest helps align enterprise value with operating figures that include the entire consolidated subsidiary.
Cash and certain investments are generally subtracted because they are treated as assets outside the core operating business and could reduce the net cost associated with acquiring the business. The exact treatment depends on the calculation method and how the assets are classified.
Why Enterprise Value Matters in Stock Valuation
Investors and analysts use enterprise value to compare the values of whole businesses. This can be useful when companies have very different amounts of debt and cash.
For example, two companies could have the same market capitalization even though one has substantial debt and the other has a large cash balance. Looking only at their common shares would hide that difference. Enterprise value incorporates those financing and cash positions into the comparison.
EV also provides a company-wide basis for valuation multiples. It can be compared with operating measures that relate to all capital providers rather than only common shareholders.
Enterprise value is not a complete investment analysis or a predictor of future returns. It is one valuation input that must be interpreted alongside profitability, cash flow, business quality, financial risks, and other relevant information.
How to Calculate Enterprise Value
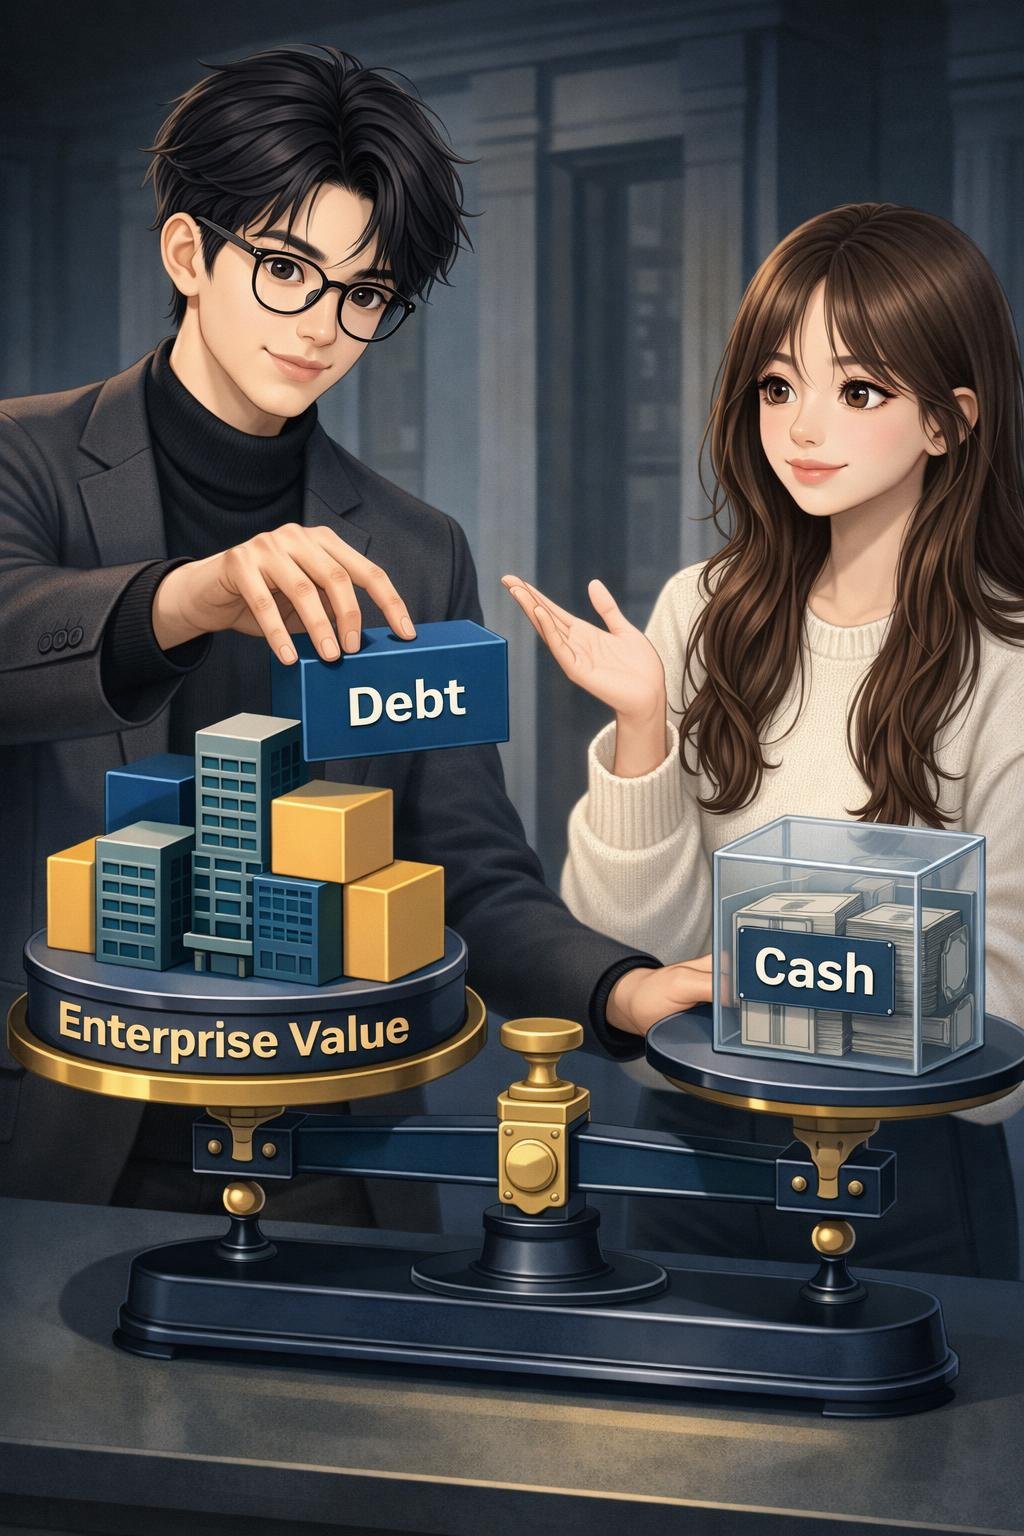
A commonly used basic formula is:
Enterprise value = Market capitalization + Debt − Cash and cash equivalents
A broader version may be written as:
Enterprise value = Market capitalization + Debt + Preferred equity + Minority interests − Cash and investments
- Market capitalization is the market value of the company’s outstanding common shares.
- Debt represents relevant borrowing claims, such as short-term and long-term interest-bearing obligations included under the selected methodology.
- Preferred equity is an ownership claim with features that differ from common stock.
- Minority interests represent outside ownership in consolidated subsidiaries that the parent company does not own completely.
- Cash and investments are subtracted when they are classified as non-operating assets under the chosen calculation method.
The formula adds financing claims because enterprise value measures more than the common shareholders’ portion of a company. It subtracts eligible cash and investments because those assets are generally not part of the operating assets being valued.
Market values are preferable when the calculation calls for the market value of debt. However, debt may not trade actively or have an easily observed market value. Analysts sometimes substitute the debt amount reported on the balance sheet. This shortcut may be less informative when the reported amount differs substantially from the debt’s market value, particularly for a financially distressed company.
Hypothetical Enterprise Value Example
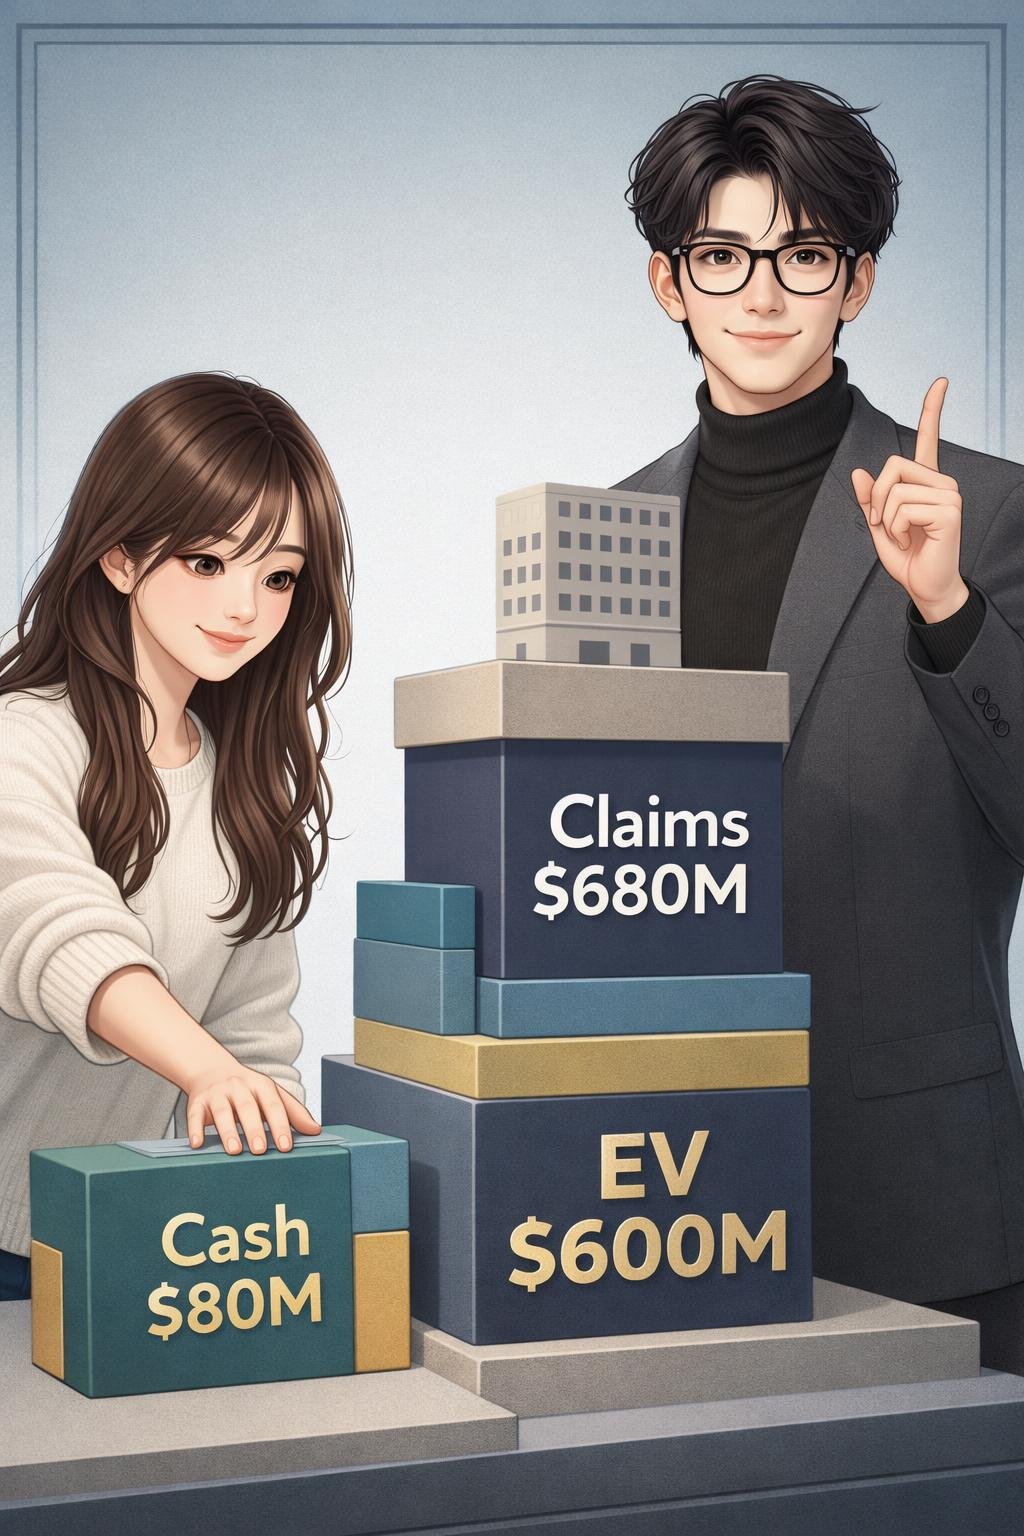
Hypothetical example: The following invented figures describe a fictional business and do not represent a real company or investment opportunity.
| Component | Hypothetical amount | Treatment |
|---|---|---|
| Market capitalization | $500 million | Add |
| Debt | $150 million | Add |
| Preferred equity | $20 million | Add |
| Minority interests | $10 million | Add |
| Cash and eligible investments | $80 million | Subtract |
The calculation is:
$500 million + $150 million + $20 million + $10 million − $80 million = $600 million
The fictional company’s enterprise value is therefore $600 million under these assumptions. This result represents an estimate of the market value of its operating business after incorporating the listed financing claims and subtracting the eligible cash and investments.
Enterprise Value, Market Capitalization, and Valuation Multiples
Market capitalization is the market value of a company’s common shares. Enterprise value starts with market capitalization but adjusts for debt, cash, and other relevant claims. As a result, the two measures can differ significantly.
| Measure | What it broadly represents |
|---|---|
| Market capitalization | The market value attributable to common shareholders |
| Enterprise value | The market value of the operating business across relevant capital providers |
Enterprise value is often used in company-wide valuation multiples. Two common examples are EV-to-EBITDA and EV-to-sales.
EBITDA means earnings before interest, taxes, depreciation, and amortization. In plain language, it is a measure based on operating earnings before certain financing, tax, and non-cash accounting expenses. The EV-to-EBITDA multiple compares enterprise value with this company-wide operating measure.
EV-to-sales compares enterprise value with company revenue. It can provide a common basis for examining businesses with different capital structures, although sales alone do not show profitability or cash generation.
The numerator and denominator of a valuation multiple should describe compatible groups of financial claims. Enterprise value is therefore generally paired with a company-wide operating measure such as EBITDA, sales, or operating cash flow. A shareholder-only measure, such as earnings available to common shareholders, is generally paired with an equity value rather than enterprise value.
How to Interpret Enterprise Value and Its Limitations
Enterprise value is a valuation input, not a stand-alone verdict about a company. A higher or lower EV can reflect differences in company size, debt, cash, operating performance, and ownership structure.
Calculations must be consistent before companies are compared. An analysis can become misleading if one company’s EV includes preferred equity or minority interests while another company’s calculation omits similar claims.
The comparison group also matters. Companies should have reasonably comparable business models, operating economics, and accounting characteristics. Even companies in the same broad industry can have important differences that affect their valuation multiples.
The operating metric paired with EV must suit the question being studied. EV-to-sales does not account for differences in profit margins. EV-to-EBITDA leaves out some expenses and reinvestment needs, so it is not a substitute for analyzing cash flow, capital spending, or financial statements.
Interpretation may also require context about profitability, expected cash-flow growth, capital structure, and financing costs. These factors can help explain why companies trade at different enterprise-value multiples.
Debt estimates and accounting classifications can create additional limitations. Book debt may differ from market debt, and analysts may classify leases, investments, pensions, or other items differently. Comparisons are more useful when the same well-defined method is applied throughout.
Common Enterprise Value Misunderstandings
- Enterprise value is not the same as market capitalization. Market capitalization covers common equity, while EV adjusts for debt, cash, and other relevant claims.
- Enterprise value is not necessarily a literal acquisition price. A real transaction may include a negotiated premium, transaction costs, financing arrangements, liabilities, asset adjustments, and other terms that the standard EV formula does not capture.
- A lower EV multiple does not automatically identify a better investment. The difference could reflect slower growth, weak profitability, higher business risk, accounting differences, or other factors.
- EV should not be mixed carelessly with shareholder-only metrics. Enterprise value relates to multiple capital providers, so it should generally be compared with a company-wide operating measure.
A consistent formula and appropriate financial context are necessary for enterprise value to be meaningful.
Frequently Asked Questions About Enterprise Value
Can enterprise value be negative?
Yes. A basic EV calculation can produce a negative result if the cash and eligible investments being subtracted exceed the combined value of common equity, debt, and other included claims. Such a result requires careful review of the company’s circumstances and the classifications used in the calculation.
Why is cash subtracted from enterprise value?
Eligible cash is generally subtracted because it is treated as a non-operating asset that reduces the net value attributed to the operating business. Not every cash-like or investment asset is necessarily treated the same way, so the methodology should be stated clearly.
Is all debt included in enterprise value?
The answer depends on the chosen definition and available financial information. Calculations commonly include relevant interest-bearing debt, but analysts may differ in their treatment of leases, pension obligations, convertible securities, and other financing items. Consistency is essential when comparing companies.
How often does enterprise value change?
Enterprise value can change whenever its components change. Market capitalization can move with the share price and number of outstanding shares, while debt, cash, preferred equity, and minority interests can change as the company finances its operations or reports updated financial information.
Can EV-to-EBITDA be used for every industry?
No single valuation multiple is suitable for every industry or company. EV-to-EBITDA may be less informative when EBITDA does not reflect important operating costs, asset requirements, or industry-specific economics.
Can EV-to-sales be used for every industry?
EV-to-sales can be calculated for many businesses with revenue, but it does not account for differences in margins or profitability. Industry economics and company-specific context are still necessary.
References
- Financial meaasures & ratios — https://pages.stern.nyu.edu/~adamodar/New_Home_Page/definitions.html
- Market-Based Valuation: Price and Enterprise Value Multiples | CFA Institute — https://www.cfainstitute.org/insights/professional-learning/refresher-readings/2026/market-based-valuation-price-enterprise-value-multiples
Key Takeaway
Enterprise value estimates the market value of a company’s operating business by incorporating more than common equity alone. It generally adds relevant financing claims, such as debt, and subtracts eligible cash and investments.
EV is most useful when it is calculated consistently, paired with an appropriate company-wide financial metric, and considered alongside profitability, cash flow, capital structure, financing costs, and other financial context.
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only. They should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.