
What Is a Balance Sheet?
A balance sheet is a financial statement that shows an entity’s financial position at a specified point in time. It lists what the entity owns, the financial obligations it owes, and the amount remaining for its owners or represented as its net position.
Unlike a statement that covers activity over a month, quarter, or year, a balance sheet is tied to a particular date. It provides a snapshot rather than a record of everything that happened during a period.
What a Balance Sheet Shows

A balance sheet groups financial information into three main categories: assets, liabilities, and equity or net position.
- Assets are resources the entity owns or controls, such as cash, inventory, equipment, or amounts customers owe.
- Liabilities are obligations owed to other parties, such as unpaid bills, loans, or bonds.
- Equity is the residual amount associated with the owners after liabilities are subtracted from assets. Some entities and public-sector statements use the term net position instead.
In simple terms, the statement shows what an entity has, what it owes, and the residual financial interest at the reporting date.
Why Balance Sheets Matter to Investors
Investors encounter balance sheets in annual reports, quarterly reports, and other financial disclosures. The statement helps readers examine the resources available to a company and the obligations that may place claims on those resources.
For example, a reader can examine the amount and types of cash, inventory, property, debt, and other obligations reported by a company. This can provide useful context about how the business is financed and whether it relies more heavily on borrowing or owner-provided capital.
Balance-sheet information can also help readers identify questions that require further investigation. A large increase in inventory, debt, or amounts owed by customers may be important, but its meaning depends on the company, its industry, the reporting period, and the explanations in the financial statement notes.
A balance sheet supports financial analysis, but it does not by itself determine whether a security is suitable for any particular investor.
How a Balance Sheet Works
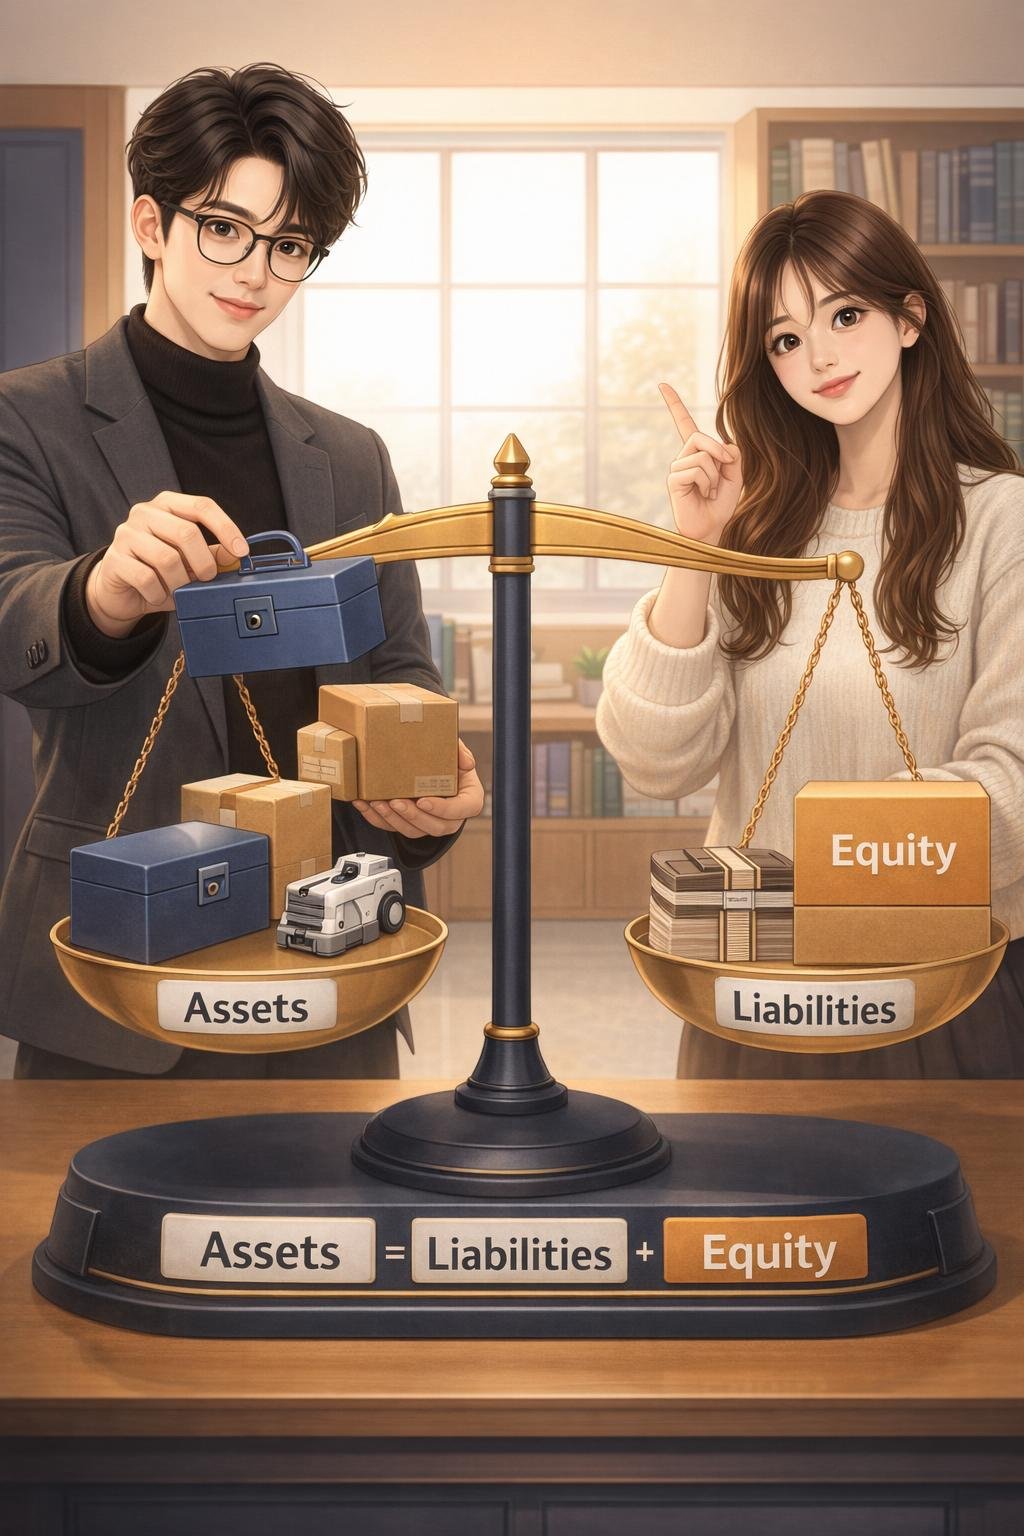
A balance sheet is built around the accounting relationship:
Assets = Liabilities + Equity
The two sides balance because an entity’s resources are financed through obligations to outside parties, owners’ interests, or a combination of both. The exact labels and presentation can vary by entity and reporting framework.
Assets
Assets are economic resources owned or controlled by the entity. Balance sheets often separate assets expected to be used, collected, or converted into cash relatively soon from longer-term assets such as property and equipment.
Liabilities
Liabilities are existing obligations to transfer cash, goods, or services to another party. They may include accounts payable, borrowed money, accrued expenses, and other financial commitments.
Equity or net position
Equity is the residual amount after liabilities are subtracted from assets. For a corporation, the equity section may contain contributed capital and accumulated results, with exact terminology depending on the reporting framework. Government and other public-sector statements may instead report net position.
The statement date
Every balance sheet relates to a specified date. A balance sheet dated at the end of a fiscal year reports the amounts recognized on that date, not an average for the entire year.
The reporting date is therefore essential when interpreting every amount on the statement.
How to Read a Balance Sheet
- Identify the statement date. Confirm the exact date represented and whether comparative dates are also shown.
- Review the assets. Look at the types of resources reported, not just the total. Consider which assets are cash or may become cash and which are intended for longer-term use.
- Review the liabilities. Examine short-term obligations, longer-term borrowing, and other significant claims against the entity’s resources.
- Examine equity or net position. Check the residual amount and its components rather than treating the total as a standalone conclusion.
- Compare relevant periods when available. Changes between reporting dates can reveal areas that deserve attention, although a change does not explain its own cause.
- Investigate important line items. Read the supporting notes and other statements to understand accounting policies, restrictions, maturity details, and unusual changes.
The goal is not simply to decide whether a number is large or small. The goal is to understand what the number represents and how it relates to the entity’s activities and obligations.
Hypothetical Balance Sheet Example
Hypothetical educational example: The following simplified figures describe a fictional business called Example Workshop. They are not real company financial data.
| Category | Hypothetical amount |
|---|---|
| Cash | $30,000 |
| Inventory | $20,000 |
| Equipment | $50,000 |
| Total assets | $100,000 |
| Unpaid supplier bills | $15,000 |
| Business loan | $25,000 |
| Total liabilities | $40,000 |
| Residual equity | $60,000 |
Example Workshop has $100,000 of total assets and $40,000 of total liabilities in this fictional snapshot. Subtracting liabilities from assets leaves $60,000 of residual equity.
The accounting relationship is therefore $100,000 of assets equal to $40,000 of liabilities plus $60,000 of equity. This example demonstrates the structure of a balance sheet, but it does not indicate whether the fictional business would be a suitable investment.
Related Financial Statement Concepts
Assets
Assets are resources owned or controlled by an entity. Their reported amounts are based on applicable accounting rules and should not automatically be interpreted as current sale prices.
Liabilities
Liabilities are obligations owed to lenders, suppliers, employees, governments, customers, or other parties. Details such as payment timing and conditions may appear in the accompanying notes.
Equity or net position
Equity or net position is the residual amount after recognized liabilities are deducted from recognized assets. It is an accounting measure and is not necessarily the same as the market value of a company.
Reporting date
The reporting date identifies when the balance-sheet snapshot applies. Comparing amounts from different dates requires attention to the periods, accounting policies, and events affecting each statement.
Other financial statements
An income statement reports revenue, expenses, and profit or loss over a period. A cash flow statement reports cash received and cash used over a period. A statement of changes in equity explains changes in owners’ equity during a period.
These statements and their notes provide context that a point-in-time balance sheet cannot supply on its own.
Common Balance Sheet Misunderstandings
A balance sheet does not show a company’s stock-market value
Balance-sheet equity is an accounting amount. A public company’s market value is based on its shares and market price, so it can differ substantially from reported equity.
A balance sheet does not directly show profitability
The balance sheet may contain accumulated amounts affected by prior results, but it does not present revenue and expenses for the reporting period. Readers generally look to the income statement for that information.
A balance sheet does not show all cash movement
Cash is usually listed as an asset, but the ending cash balance does not explain all sources and uses of cash during the period. The cash flow statement provides that additional detail.
A balanced statement does not mean the entity has no financial problems
The accounting equation must balance as part of the statement’s structure. That mathematical balance does not prove that an entity can easily meet its obligations or that its financial condition is strong.
Balance-sheet figures need interpretation and should not be used alone to judge an investment.
What a Balance Sheet Cannot Tell You by Itself

A balance sheet is limited to a snapshot at a specified date. Amounts can change after that date, and the statement alone may not explain the transactions or business conditions that produced them.
Important details may also appear in the financial statement notes. The notes can explain accounting policies, debt terms, commitments, restrictions, estimates, and other matters needed to understand reported line items.
Readers may need to compare several reporting dates to identify changes. They should also review the income statement, cash flow statement, statement of changes in equity, and relevant management explanations when available.
No single asset, liability, or equity figure reliably predicts a company’s future operating results or stock performance. Each amount requires context from the reporting period, the entity’s activities, and the rest of its financial information.
Balance Sheet FAQ
Does a balance sheet cover a day or a period?
A balance sheet applies to a specified date. Statements such as the income statement and cash flow statement instead describe activity over a period with a beginning and an end.
Can an individual have a balance sheet?
The same basic idea can be applied to an individual, business, government, or other economic entity. The relevant assets, liabilities, and residual amount will differ according to the type of entity.
What does negative equity or negative net position mean?
At a basic level, it means recognized liabilities exceed recognized assets on the statement date. The reasons and implications depend on the entity, its accounting framework, its obligations, and other financial information, so the figure requires further context.
Is cash the same as total assets?
No. Cash may be one asset category, while total assets can also include amounts owed by customers, inventory, investments, property, equipment, and other recognized resources.
Where can investors find official company balance sheets?
Public companies generally include balance sheets in their official financial reports and regulatory filings. In the United States, readers can review company investor-relations materials and filings available through the official U.S. Securities and Exchange Commission filing system. The statement date, form type, reporting period, and accompanying notes should all be checked.
Why might two entities use different balance-sheet labels?
Terminology and presentation can vary with the type of entity and applicable reporting framework. For example, a business may report shareholders’ equity, while a public-sector statement may use net position.
When labels differ, the statement’s definitions and supporting notes can clarify what each amount represents.
References
- Balance sheet | U.S. Bureau of Economic Analysis (BEA) — https://www.bea.gov/help/glossary/balance-sheet
- Financial Statements of the United States Government for the Fiscal Years Ended September 30, 2025, and 2024 | Bureau of the Fiscal Service — https://fiscal.treasury.gov/accounting/us-financial-report/balance-sheets
- Balance Sheet Framework – GOV.UK — https://www.gov.uk/government/publications/balance-sheet-framework
These official sources provide definition, public-sector reporting, and balance-sheet management context.
Key Takeaway
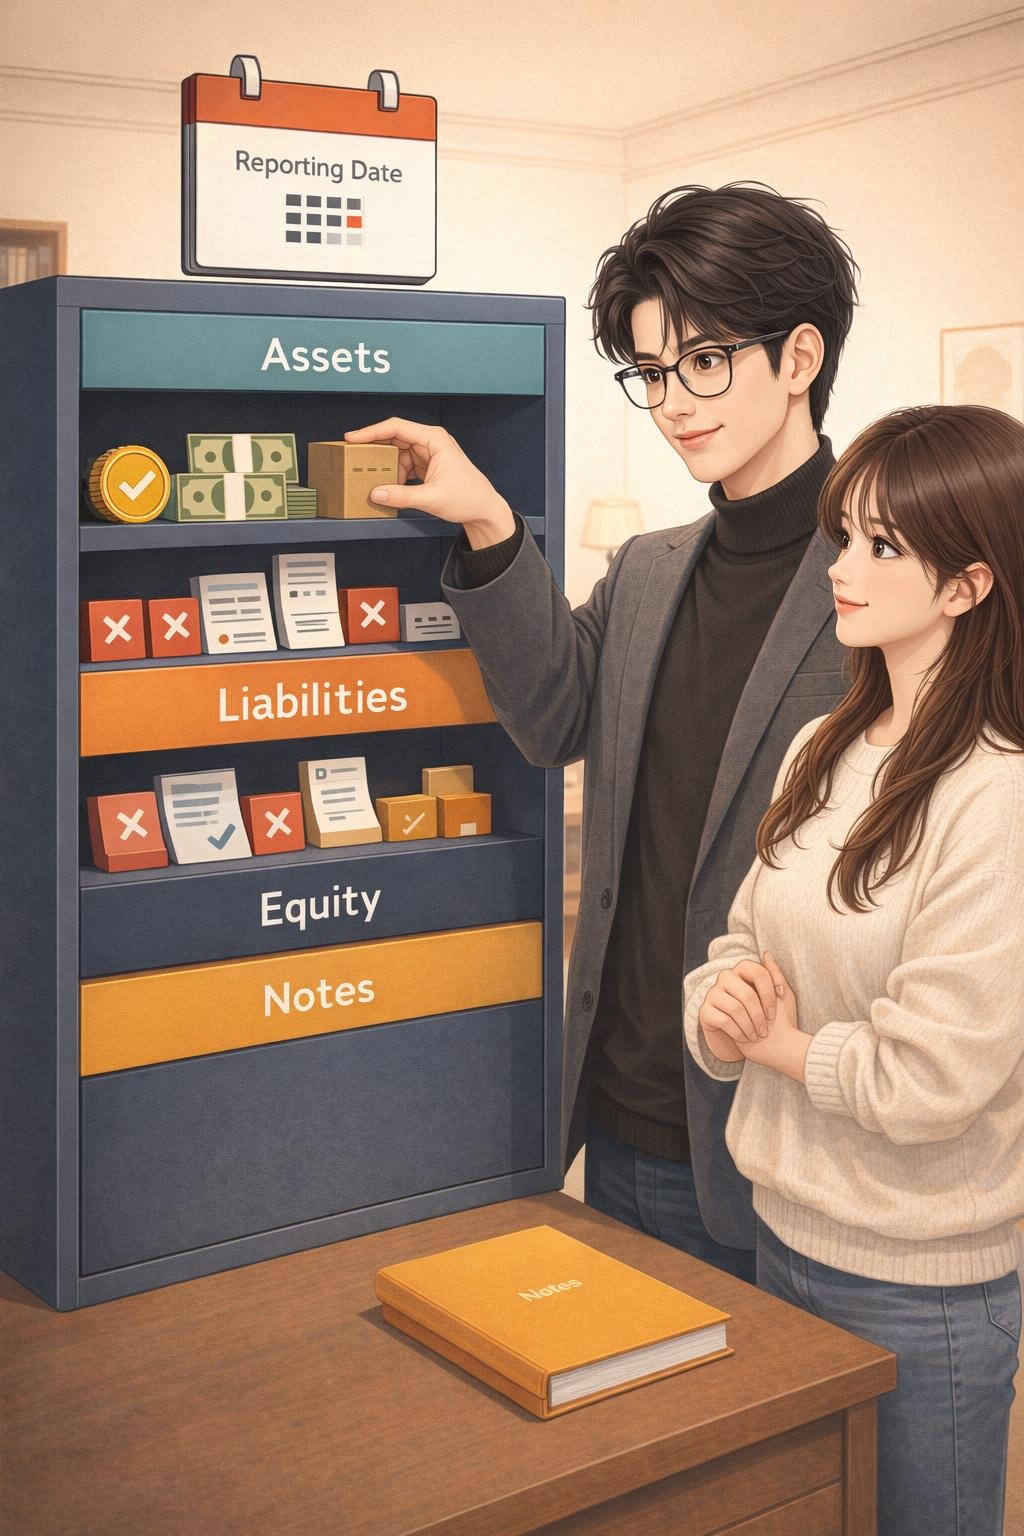
A balance sheet is a point-in-time financial statement showing an entity’s assets, liabilities, and residual equity or net position. It can help readers understand resources, obligations, and financing, but every amount must be interpreted using the statement date, supporting notes, relevant comparisons, and other financial statements.
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only. They should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.