
What Is a Capital Gain?
A capital gain is the profit earned when an investment is sold for more than its cost. In stock investing, it generally occurs when the proceeds from selling shares are greater than the investor’s adjusted basis in those shares.
A rising stock price does not guarantee that an investor will ultimately make money. The price can change before the stock is sold, and transaction-related adjustments may affect the final gain or loss.
What a Capital Gain Means in Stock Investing
When an investor purchases stock, the amount used to determine the investment’s cost is called its basis. That basis may later be adjusted by certain events or transactions, which is why tax materials often use the term adjusted basis.
Sale proceeds are the amount received from selling the stock, subject to any applicable transaction-related adjustments. Comparing the sale proceeds with the adjusted basis shows whether the sale produced a gain or loss.
If the sale proceeds are higher than the adjusted basis, the difference is a capital gain. If the proceeds are lower, the difference is a capital loss. A sale generally establishes, or realizes, the result for the investment.
Why Capital Gains Matter to Investors
Capital gains help investors measure the result of selling an investment. A brokerage record may show the proceeds from a stock sale, the reported basis, the purchase and sale dates, and the resulting gain or loss.
The term is also important because selling stock may create tax and reporting consequences. The holding period and the investor’s individual tax circumstances can affect how the transaction is classified and treated.
Capital gains are only one possible outcome. Stock prices can decline, and selling stock below its adjusted basis generally creates a capital loss. Investing therefore involves the possibility of losing some or all of the amount invested.
How a Capital Gain Is Calculated
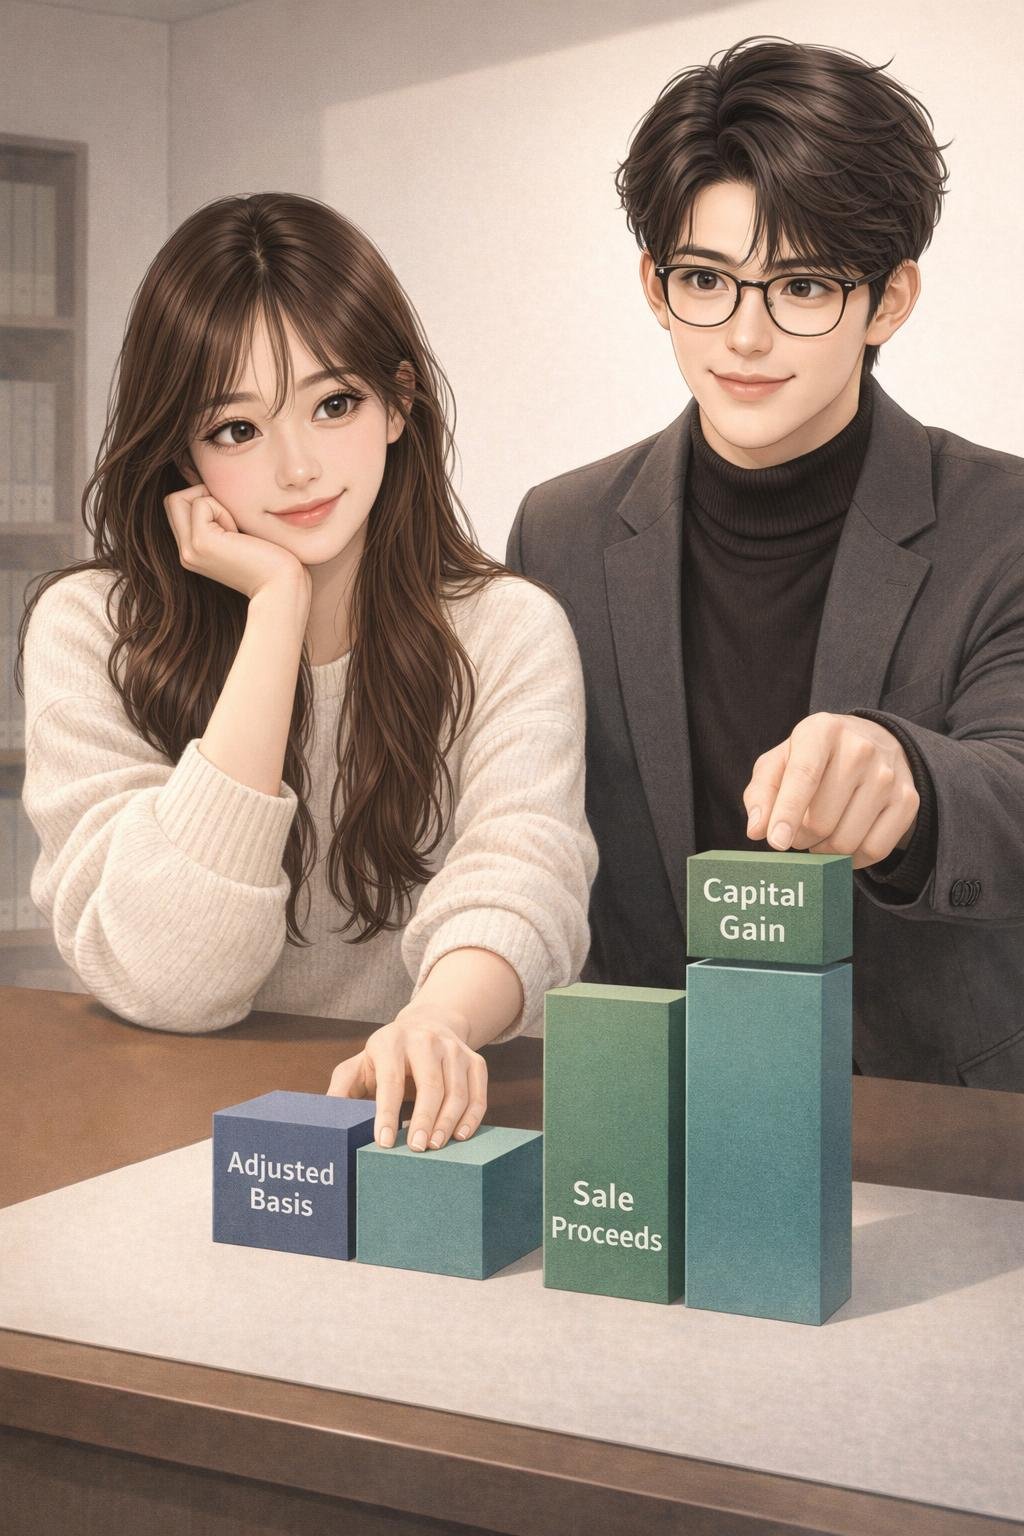
The basic relationship is:
Capital gain or loss = sale proceeds − adjusted basis
- If the result is positive, the sale produced a capital gain.
- If the result is negative, the sale produced a capital loss.
- If the amounts are equal, there is generally no gain or loss under this basic calculation.
The adjusted basis is not always identical to the stock’s original quoted purchase price. Applicable transaction costs, adjustments, or other events may affect the amount used in the calculation. Investors should use reliable records rather than relying only on memory or a historical price chart.
Hypothetical Capital Gain Example
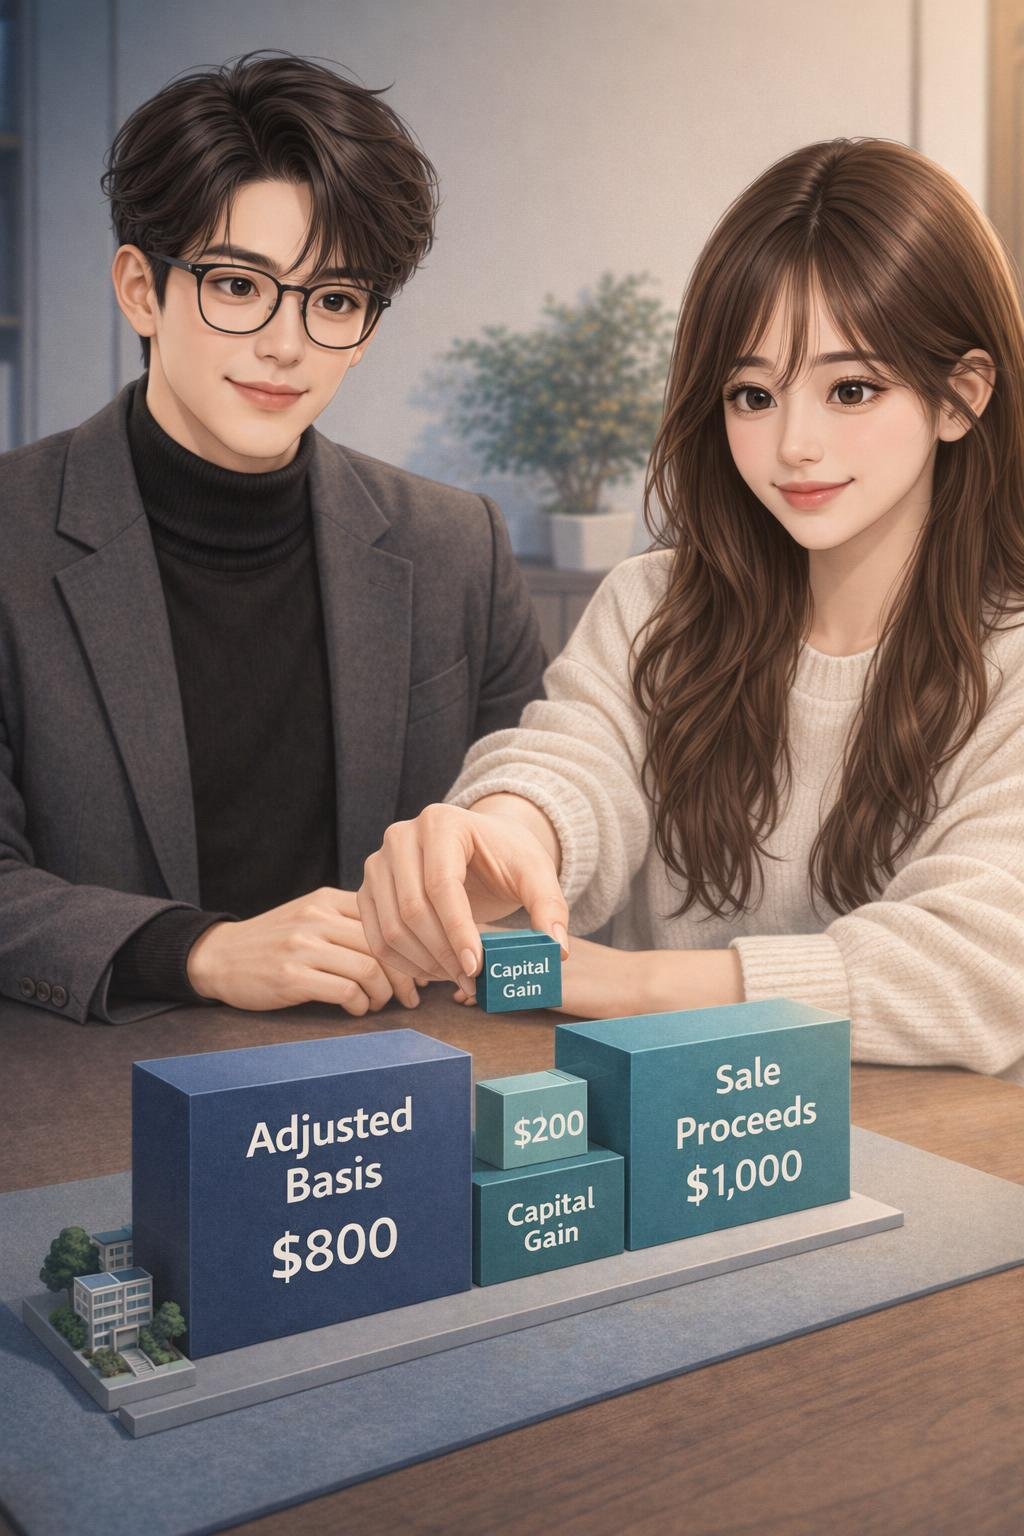
Hypothetical example: An investor purchases shares in a fictional company for a total adjusted basis of $800. The investor later sells all the shares for total proceeds of $1,000.
The basic calculation is $1,000 minus $800, resulting in a $200 capital gain.
These figures are fictional and are provided only to demonstrate the calculation. They are not real market data, and the example does not imply that a stock will rise or produce a profit. Applicable adjustments could also change the final tax calculation.
Realized Gains, Unrealized Gains, and Capital Losses

Capital appreciation means that an investment has increased in value. If a stock’s market price rises while the investor continues to own it, the increase is commonly described as an unrealized gain. It can change as the market price changes.
A realized gain generally results when the stock is sold for more than its adjusted basis. The sale converts the price increase from an on-paper change into a completed transaction.
A capital loss generally occurs when stock is sold for less than its adjusted basis. Capital losses may have tax consequences, but the outcome depends on applicable rules and the investor’s circumstances.
Adjusted basis is the amount used to measure gain or loss after accounting for applicable adjustments. Accurate basis information is therefore important when evaluating a sale.
Capital gains are also different from dividends. A capital gain comes from selling an investment above its adjusted basis. A dividend is a distribution made by a company to eligible shareholders. The two can have different tax treatment and reporting requirements.
Short-Term and Long-Term Capital Gains
The Internal Revenue Service generally classifies a gain or loss as short-term when the investment was held for one year or less. It is generally classified as long-term when the investment was held for more than one year.
The distinction matters for U.S. federal taxes. Net short-term capital gains are generally taxed as ordinary income, while lower federal tax rates may apply to net long-term capital gains. The applicable treatment depends on current tax law and the taxpayer’s circumstances.
Tax rates, forms, thresholds, and rules can change. Investors should consult current IRS information and consider seeking help from a qualified tax professional for questions about their own transactions.
Common Capital Gain Misunderstandings
- A price increase is not necessarily a realized gain. If the investor still owns the stock, the increase is generally unrealized and can change before a sale occurs.
- The taxable gain may not simply equal the sale price minus the originally quoted purchase price. The calculation generally compares sale proceeds with adjusted basis, and applicable adjustments may affect both amounts.
- Capital gains are not dividends. Capital gains arise from changes in an investment’s value followed by a sale, while dividends are company distributions to eligible shareholders.
- A possible capital gain does not make stock investing risk-free. Stock prices can fall, and an investor can experience a capital loss or lose principal.
Understanding these distinctions helps investors interpret brokerage records and tax information more accurately without assuming that every price increase is a completed profit.
Capital Gain FAQ
When does a stock gain become realized?
A gain generally becomes realized when the stock is sold for more than its adjusted basis. Before the sale, a higher market value is generally considered an unrealized gain.
Does selling stock below its basis create a capital loss?
Selling stock for less than its adjusted basis generally creates a capital loss. The tax treatment of that loss depends on applicable rules and the investor’s individual circumstances.
How does the holding period affect a capital gain?
The holding period determines whether the gain is generally classified as short-term or long-term. An investment held for one year or less generally produces a short-term result, while one held for more than one year generally produces a long-term result.
What records may an investor need?
Useful records may include documents showing purchase and sale dates, purchase amounts, sale proceeds, and applicable basis adjustments. Brokerage tax documents may provide some of this information, but investors should review the records for completeness and retain supporting documents when appropriate.
Where are stock capital transactions generally reported?
According to IRS guidance, most capital transactions are generally reported on Form 8949 and summarized on Schedule D. Forms and reporting requirements can change, so investors should check current IRS instructions rather than relying only on an earlier year’s process.
Does having a capital gain always mean tax is owed?
Not necessarily. The result can depend on other gains and losses, the holding period, the type of account, applicable tax rules, and the taxpayer’s circumstances. Current IRS guidance or a qualified tax professional should be used for an individual tax conclusion.
Key Takeaway
A capital gain generally occurs when stock is sold for more than its adjusted basis. Understanding the sale proceeds, adjusted basis, holding period, and supporting records helps an investor identify and classify the result.
A gain may also create tax and reporting considerations, but rules and individual outcomes vary. Stock investing still involves risk, including the possibility that the stock will be sold at a loss.
References
- Capital Gain | Investor.gov: https://www.investor.gov/introduction-investing/investing-basics/glossary/capital-gain
- Stocks – FAQs | Investor.gov: https://www.investor.gov/introduction-investing/investing-basics/investment-products/stocks
- Topic no. 409, Capital gains and losses | Internal Revenue Service: https://www.irs.gov/taxtopics/tc409?ref=maximise
- Publication 550 (2025), Investment Income and Expenses | Internal Revenue Service: https://www.irs.gov/publications/p550?v=6082512
Disclaimer
This article is provided for general educational and informational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy, sell, hold, or avoid any security or financial product. Financial information, company information, market conditions, fees, rules, regulations, and platform details can change. Investing involves risk, including the possible loss of principal. Verify important current information through relevant official sources and consider your circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images may be AI-generated educational illustrations provided for visual explanation only. They should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.