
An exchange-traded fund, usually called an ETF, is an investment fund that trades on a stock exchange. A fund pools money into a collection of investments, such as stocks, bonds, or other assets.
When you own a share of an ETF, you own an interest in the fund. You do not directly own each stock or bond held by the fund. The fund owns those assets on behalf of its shareholders.
An ETF can be compared to a basket. Instead of buying every item separately, an investor can buy one share representing a small part of the entire basket. For example, a stock ETF might hold shares in dozens or hundreds of companies.
ETFs are called “exchange-traded” because their shares are bought and sold on exchanges during the trading day. This makes them similar to individual stocks. Their market prices can rise or fall while the exchange is open.
Some ETFs are designed to follow a market index. An index is a group of investments used to measure part of the market. Other ETFs follow a particular industry, geographic region, bond category, commodity, investment strategy, or other theme.
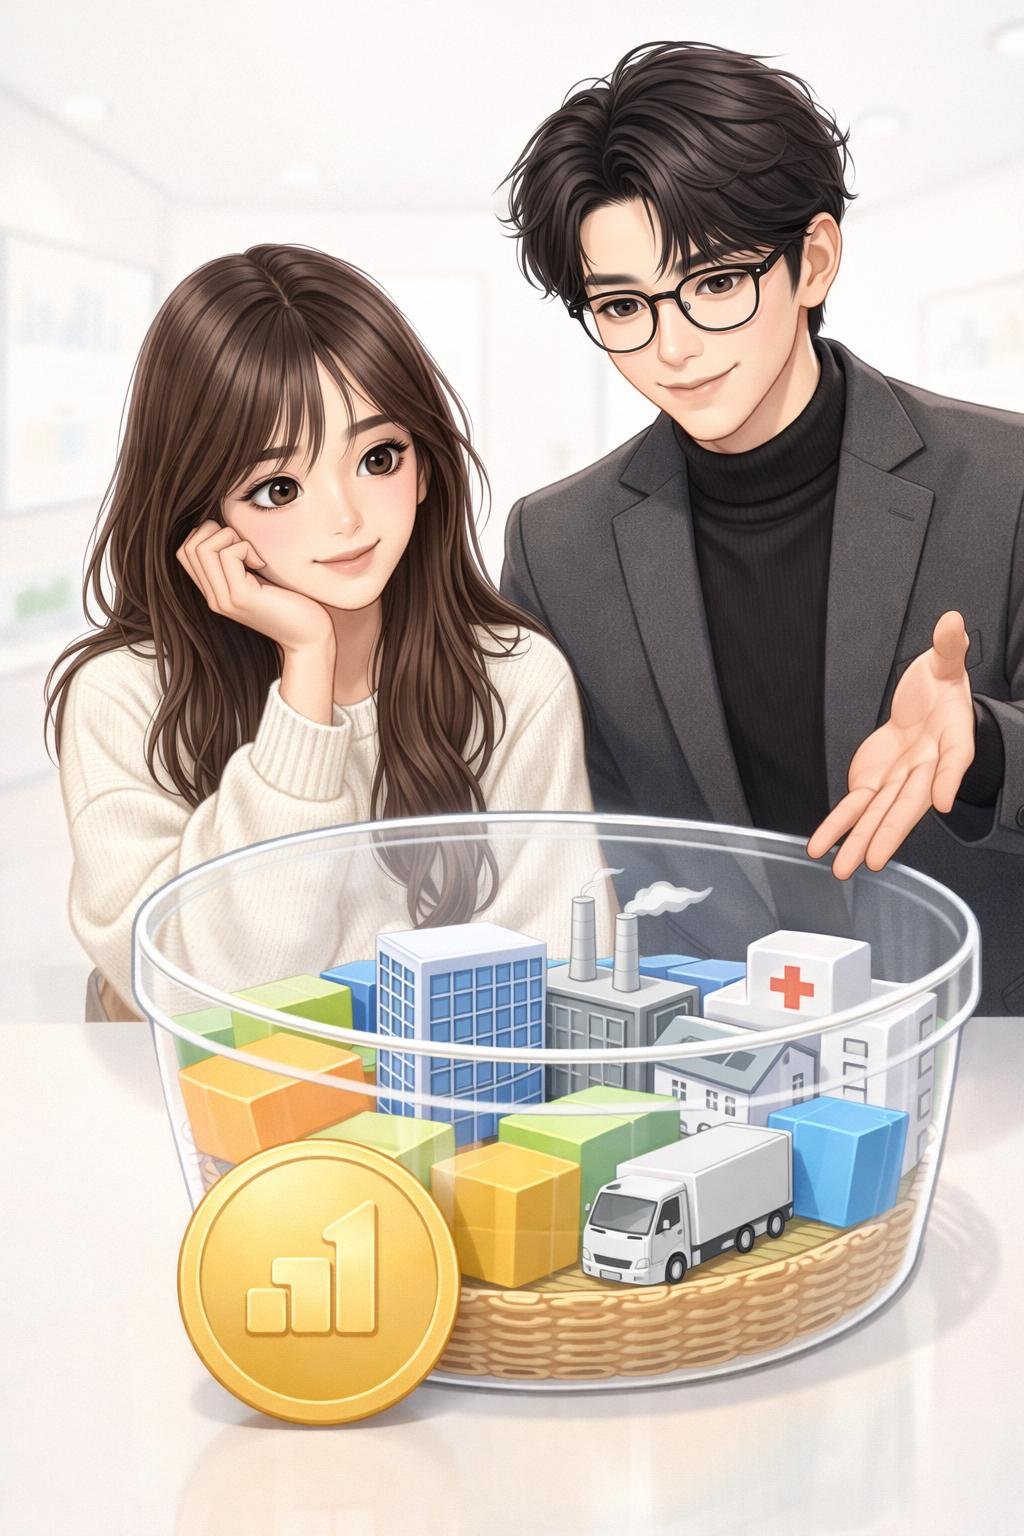
How Does an Exchange-Traded Fund Work?
An ETF is usually operated by a fund provider. The provider establishes the fund’s objective and decides which assets it will hold under stated rules.
For example, an index ETF may seek to track the performance of a specific index. The ETF typically holds the same investments as the index, or a representative selection of them. A bond ETF may hold debt issued by governments, companies, or other borrowers.
Here is the basic process:
- The ETF collects assets. Its portfolio may contain stocks, bonds, cash, commodities, derivatives, or a combination of investments.
- The fund issues shares. Each ETF share represents a proportional interest in the fund.
- The shares trade on an exchange. Investors can submit orders through brokerage accounts while the market is open.
- The market sets a trading price. Buyers and sellers influence the price throughout the day.
- The fund charges operating expenses. These costs are generally reflected in the fund’s returns rather than billed as a separate monthly payment.
Market Price and Net Asset Value
An ETF has both a market price and a net asset value, or NAV.
The market price is the price at which ETF shares trade on an exchange. It changes as investors submit buy and sell orders.
NAV represents the value of the fund’s assets after subtracting its liabilities, or financial obligations. NAV per share is calculated as follows:
NAV per share = (Total asset value − Total liabilities) ÷ Number of ETF shares
In ordinary language, the fund adds up what it owns, subtracts what it owes, and divides the result by the number of shares.
An ETF’s market price may be slightly above or below its NAV per share. A price above NAV is called a premium. A price below NAV is called a discount.
Creation and Redemption
ETFs have a special process designed to help keep their market prices close to the value of their holdings. Large financial institutions known as authorized participants can generally create or redeem large blocks of ETF shares.
In a creation, an authorized participant usually delivers a specified collection of assets or cash to the ETF. In return, it receives a large block of ETF shares. In a redemption, the process works in reverse.
This activity can help reduce large differences between the market price and NAV. However, it does not guarantee that the two values will always match. Premiums and discounts may become larger when markets are volatile, when underlying assets are difficult to trade, or when price information is limited.
Simple Example
Assume a hypothetical ETF owns stocks worth $10 million. It has liabilities of $100,000 and 990,000 ETF shares outstanding. These figures are simplified and do not represent a real fund.
Its NAV per share would be:
($10,000,000 − $100,000) ÷ 990,000 = $10 per share
If ETF shares trade on the exchange for $10.05, the market price is $0.05 above NAV. The ETF is trading at a premium.
The premium percentage can be calculated as:
Premium percentage = (Market price − NAV) ÷ NAV × 100
Using the hypothetical figures:
($10.05 − $10.00) ÷ $10.00 × 100 = 0.5%
If the ETF instead trades at $9.95, it is trading at a discount of 0.5% to its $10 NAV.
Now assume the ETF holds 100 different stocks in varying amounts. An investor who owns one ETF share has an indirect interest in that complete portfolio. The investor does not own one full share of every company. The investor owns one share of the fund, and the fund owns the underlying stocks.
If the value of the portfolio rises, the ETF’s NAV will generally rise. If the portfolio falls in value, its NAV will generally fall. The market price may move in a similar direction, although supply, demand, and market conditions can create short-term differences.
Why Does an Exchange-Traded Fund Matter?
Beginners often encounter ETFs in brokerage accounts, retirement accounts, financial news, and discussions about diversification.
Diversification means spreading money among multiple investments rather than relying on only one. Because one ETF may hold many assets, it can provide diversification through a single tradable security.
However, owning an ETF does not automatically mean a portfolio is well diversified. An ETF may focus narrowly on one industry, country, commodity, or strategy. Several ETFs may also hold many of the same investments.
ETFs can help investors gain exposure to a broad market or a specific market category. Exposure means being financially affected by the performance of a group of assets.
An ETF also provides information about a defined portfolio. Fund documents generally describe its objective, principal holdings, risks, expenses, and investment approach. Investors may use this information to understand what part of the market the fund is designed to represent.
An ETF’s name alone cannot provide a complete picture. Two funds with similar names may hold different assets, follow different rules, charge different expenses, or carry different risks. An ETF also cannot predict future returns or eliminate the possibility of loss.
How Beginners Can Interpret an Exchange-Traded Fund
Begin by identifying what the ETF is intended to hold or track. A broad-market stock ETF is different from a fund focused on one industry. A bond ETF is different from a stock ETF because bonds and stocks respond differently to business conditions, interest rates, and other risks.
Next, review how concentrated the portfolio is. Concentration refers to how much of the fund is placed in a small number of investments or one market category. A fund holding hundreds of securities may still be concentrated if a few large holdings represent a substantial part of its value.
The expense ratio is another important detail. It shows the fund’s annual operating expenses as a percentage of its average assets. For example, a hypothetical 0.25% expense ratio represents $2.50 per year for every $1,000 invested, assuming the amount stays at $1,000. Actual costs reflected in returns will vary as the investment’s value changes.
Trading costs can also matter. A brokerage firm may charge transaction fees. In addition, investors may experience a bid-ask spread. The bid is the highest current price a buyer is offering. The ask is the lowest current price a seller is willing to accept. The difference is the spread.
Beginners may also examine trading volume and liquidity. Liquidity describes how easily an asset can be traded without causing a large price change. An ETF’s liquidity depends on both trading in its shares and the liquidity of its underlying assets.
No single expense ratio, trading volume, premium, discount, or number of holdings makes every ETF suitable or unsuitable. Meaningful interpretation depends on the fund’s objective, portfolio, risks, structure, market conditions, and the period being measured.
Limitations and Common Mistakes
- Assuming every ETF is diversified: Some ETFs hold a broad market, while others focus on a narrow sector or a small group of assets. A narrow ETF can be highly sensitive to one industry or theme.
- Confusing an ETF with its holdings: Buying an ETF share means owning an interest in the fund. It does not create direct ownership of each underlying security.
- Ignoring price differences: The market price can differ from NAV. Premiums and discounts may become more noticeable during market stress or when underlying markets are closed.
- Looking only at the expense ratio: Operating expenses are important, but they are not the only costs. Bid-ask spreads, brokerage fees, premiums, discounts, and taxes may also affect an investor’s result.
- Assuming index tracking is exact: An index ETF may not produce exactly the same return as its index. Expenses, trading costs, taxes, portfolio adjustments, and sampling methods can create a difference called tracking error.
- Treating similar names as identical: ETFs with similar labels may use different indexes, weighting methods, holdings, or definitions.
- Overlooking distributions: A fund may pass along dividends, interest, or capital gains to shareholders. A dividend is a payment from a company. Interest is income paid by a borrower. A capital gain may occur when an asset is sold for more than its cost. Distributions and their tax treatment can vary.
- Misunderstanding leveraged or inverse ETFs: Leveraged ETFs seek a multiple of a stated benchmark’s return, often for a daily period. Inverse ETFs seek to move in the opposite direction of a benchmark, usually for a stated period. Compounding can cause longer-term results to differ greatly from a simple multiple or opposite of the benchmark’s total change.
- Assuming trading access removes risk: The ability to trade during the day does not prevent losses. An ETF’s price can decline because of changes in its holdings, interest rates, currencies, credit conditions, or investor demand.
Comparisons can also be misleading when ETFs follow different indexes or report data for different periods. A stock ETF should not automatically be compared with a bond ETF as if they have the same purpose or risks. Past performance describes an earlier period and does not determine future results.
Related Beginner Terms
- Mutual fund: Another pooled investment fund. Traditional mutual fund transactions generally occur at a calculated end-of-day NAV, while ETF shares trade throughout the market day.
- Index: A defined group of securities used to represent or measure a market segment. An index itself is a measurement, while an index ETF is an investable fund that seeks to track it.
- Stock: A security representing an ownership interest in a company. A stock ETF can hold shares of many companies.
- Bond: A debt investment representing money lent to a government, company, or other issuer. Bond ETFs pool multiple bonds in one fund.
- Dividend: A payment that a company may make to shareholders. An ETF may collect dividends from its holdings and distribute income according to the fund’s policies.
- Market order: An instruction to trade promptly at the best available price. The final price is not guaranteed.
- Limit order: An instruction to trade only at a specified price or better. The price is controlled, but the order may not be completed.
- Portfolio: The complete collection of investments owned by a person or fund. An ETF’s holdings form its portfolio.
FAQ
Is an ETF the same as a stock?
No. Both trade on stock exchanges, but they represent different things. A stock represents ownership in one company. An ETF share represents an interest in a fund that may own many investments.
Can an ETF lose value?
Yes. The value of an ETF can fall when its underlying assets decline or when market conditions affect its trading price. Diversification can spread certain risks, but it cannot eliminate all risk.
Do all ETFs follow an index?
No. Many ETFs seek to track indexes, but some are actively managed. An actively managed ETF has a management team that selects investments according to the fund’s stated strategy.
Does a low share price mean an ETF is inexpensive?
Not necessarily. Share price alone does not show whether a fund’s holdings are attractively valued. It mainly reflects the value assigned to each ETF share and the number of shares outstanding.
How does an ETF make money for shareholders?
An ETF may increase in value when its holdings rise. It may also make income distributions from dividends or interest. Neither price gains nor distributions are guaranteed.
What happens if an ETF closes?
A fund provider may decide to close and liquidate an ETF. The fund generally sells or distributes its assets and returns the remaining value to shareholders under its stated process. Prices, expenses, timing, and tax consequences may affect the final result.
Why can an ETF’s price differ from its NAV?
ETF shares trade according to market supply and demand. Differences can also arise from trading hours, market volatility, transaction costs, and difficulty valuing or trading the underlying assets.
Are ETFs tax-free?
No. ETF ownership can create taxable dividends, interest, capital gain distributions, or gains when shares are sold. Tax treatment depends on the fund, account type, transactions, and the investor’s circumstances.
Key Takeaway
An exchange-traded fund is a pooled investment that holds a portfolio of assets and trades on an exchange like a stock. It can help a beginner access a broad market or a specific category through one security.
Understanding an ETF requires looking beyond its name. Its objective, holdings, concentration, expenses, trading price, NAV, strategy, and risks all matter. An ETF can provide useful market exposure, but it cannot guarantee diversification, income, profits, or protection from loss.
Disclaimer
This article is for general educational and informational purposes only. It is not investment, financial, legal, or tax advice. Financial information, fund features, and market conditions can change. Readers should verify current information and consider their own circumstances, objectives, and risk tolerance before making financial decisions.
Image Notice: Images in this article may be AI-generated educational illustrations. They are provided for visual explanation only and should not be interpreted as exact representations of real companies, people, products, documents, financial data, or investment outcomes.